Hello, this is Adullam Consulting (formerly ADL Consulting).
"Surely that is what a company is for. If something goes wrong, the company carries it, does it not?" It is the reaction we hear most often at head office when we report a missed filing at an Indian subsidiary. Limited liability is where company law begins, and in Korea most administrative breaches do end with a fine on the company, so the assumption is a reasonable one to hold.
In India it is only half right. A great many breaches are framed not as a monetary sanction on the company but as criminal liability attaching to the officers personally. The person whose name is on the register becomes the accused, and paying the tax later does not automatically make the proceedings go away.
That is why India director liability belongs less in your compliance budget than in your posting decisions. What follows sets out where liability crosses over to the individual, with the provisions behind it.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
Not every breach stops at the company. A great many duties name an individual from the outset.
Withholding tax is the first place you will meet this. Deduct the tax and fail to pay it over, and you are exposed to prosecution carrying a term of not less than three months and up to seven years.
With GST, the size of the amount changes the nature of the process. Above ₹5 crore of evasion, the power of arrest becomes available.
Company law and factory law also name individuals. The daily charge for a late commencement filing runs against the officers as well as the company.
Size is no protection. One withholding failure kept a plant closed for six years.
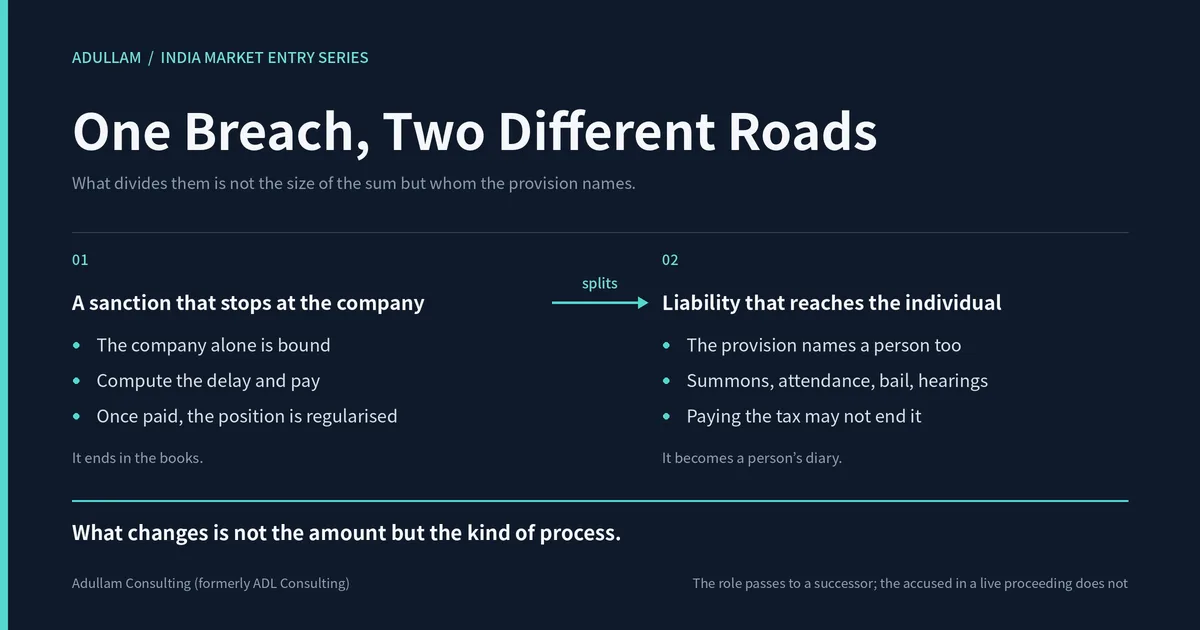
1. Administrative Sanctions and Criminal Liability Part Company at a Different Point
In an earlier article we set out why penalties in India are not one-off fines but charges that accrue in proportion to time. One area was deliberately left out of that piece: the place where what changes is not the amount but the kind of process that follows.
An administrative sanction ends in the company's books. Compute the delay, pay, and the position is regularised. A provision that carries criminal liability, by contrast, summons a person. Summons and attendance, bail and hearings follow, and that timetable will not accommodate your reporting calendar or the length of a secondment.
The moment the difference becomes visible is usually a posting decision. A country head who has completed a term wishes to return home, and finds that a live proceeding carries their name. The role can be handed to a successor; the accused in a proceeding already commenced cannot.
This also changes who ought to be looking at the matter. Where the exposure is a sum of money, it is reasonable for the finance function to hold it and report it upward once a quarter. Where the exposure is a named individual, the question belongs with whoever decides secondments and board appointments, and it needs to be asked before the appointment rather than after the default.
2. Withholding Tax (TDS) — the First Provision You Will Meet
Withholding tax is where this arises most often. Deducting tax from payroll, from fees for services and from royalty remittances is something most subsidiaries do. The difficulty arises at the next step: paying the deducted amount over to the exchequer within the deadline.
The money is not the company's. It is money received from someone else and held for onward payment to the state. That is why Indian income-tax law treats a failure here not as late payment but under a separate penal provision. A shortfall in the company's own tax is a debt; a shortfall here is money collected for the exchequer and not passed on, and the statute is drafted accordingly.
Section 276B of the Income-tax Act, 1961 exposes a failure to pay over tax deducted at source to prosecution carrying a term of not less than three months and up to seven years. An amendment in 2024 introduced relief where payment is made before the due date for the quarterly statement, and that framework has been carried into the new Income-tax Act, 2025, in force since April 2026.
The relief should not be read too broadly. It is a provision for the company that regularises within the time allowed; it is not a route out of habitual delay. Where the quarterly deadline has already passed, the safer assumption is that the door is not open.
※ Please note — the provision and the conditions for relief are subject to amendment. You should re-confirm them against the current statute and local advice at the time of your review.
3. GST — Above a Certain Figure, the Process Itself Changes
On the GST side there is a line drawn in money. Where evasion exceeds ₹5 crore, the power of arrest under the Central Goods and Services Tax Act, 2017 becomes available.
"But we have no intention of evading anything" is the reply we most often hear. Quite so; yet the figure accumulates independently of intention. Where a treatment applied consistently over several years is subsequently disallowed, the cumulative amount reaches the line. Whether the treatment was right is something you can argue. What the amount decides is the kind of process in which you will be arguing it.
This is also why a long-running position deserves a periodic second look rather than the comfort of consistency. A treatment that no one has questioned for four years is not thereby safer; it is simply four years' worth of the same figure, and it is the total rather than any single year that is measured against the threshold.
Area | Provision | What reaches the individual |
|---|---|---|
Withholding tax (TDS) | Income-tax Act s. 276B (carried into the 2025 Act) | Prosecution carrying not less than three months and up to seven years |
GST | CGST Act ss. 69 and 132 | Power of arrest where evasion exceeds ₹5 crore |
Commencement of business | Companies Act s. 10A | ₹1,000 per day on the officers (₹50,000 on the company) |
Running a factory | Occupier duties under factories legislation | A named director is the person on whom the duty falls |
4. Company Law and Factory Law — Duties That Name a Person, Not a Company
This is not confined to tax. The declaration of commencement of business (INC-20A), due within 180 days of incorporation, is the clearest example. Under section 10A of the Companies Act, 2013 the company is liable to ₹50,000 and, separately, the officers are liable to ₹1,000 for every day the default continues. Left unattended, it is also a ground on which the registrar may strike the company off. The figures are modest. What the provision shows is that the company and the individual are named side by side.
If you operate a factory there is a further duty. Indian factories legislation places responsibility for safety and statutory compliance on a designated Occupier rather than on the company, and in practice one of the directors is named. Duties framed this way, with an individual director as the person bound, run right through the Indian statute book, and this is where the gap in awareness among Korean companies is widest. The book behind this series gives the subject a chapter of its own in Volume 3, Chapter 5.
5. "Surely It Is Different for a Large Company"
The expectation that scale prevents this is not borne out. Nokia was served with a demand of approximately ₹2,080 crore following a January 2013 tax inspection at its Sriperumbudur plant near Chennai, for failure to withhold on royalty remittances.
Date | What happened |
|---|---|
Jan 2013 | Tax inspection — demand of approximately ₹2,080 crore for failure to withhold |
Apr 2014 | Microsoft acquisition completes — with assets frozen, this plant alone is carved out of the deal |
1 Nov 2014 | Deprived of orders, the plant ceases production (8,000 people directly employed) |
2018 / 2020 | Dispute settled through the India–Finland Mutual Agreement Procedure → Salcomp acquires the plant and restarts it |
A further sales tax demand of ₹2,400 crore from the Tamil Nadu state government was layered on top. No one compensated anyone for the six years the plant stood idle.
The rules have not stood still. The retrospective taxation disputes brought by Vodafone and Cairn Energy went as far as investor-state arbitration, and the Permanent Court of Arbitration found for the companies in September and December 2020 respectively; the Cairn award, of some US$1.2 billion plus interest and costs, reached the point at which the company moved to attach Indian state assets abroad. In August 2021 the Indian government repealed the 2012 retrospective taxation provisions through the Taxation Laws (Amendment) Act, 2021 and refunded ₹7,900 crore to Cairn Energy. That is a step forward. What it does not return is the time lost in the interval.
6. What We Would Therefore Recommend
Once a proceeding has commenced, no decision of the company will reverse it on its own. Three things can be done in advance.
First, treat appointment to the board as an allocation of risk rather than a matter of seniority. Before a name goes on the register because of the person's grade, it should be settled what that person will be told and how often.
Second, have the items that carry personal liability reported to you as a separate set. Withholding payments, GST, the commencement filing and factory duties disappear from view when they sit in the same schedule as everything else.
Third, check for live proceedings before a term ends. Checked before the posting is decided, you still have options; checked afterwards, you have fewer.
None of the three is expensive. What makes them difficult is that each has to be done at a point when nothing appears to be wrong, which is precisely when the subject is easiest to defer.
Frequently Asked Questions (FAQ)
Q1. An officer of our Korean parent is on the board of the Indian subsidiary. Does liability reach them while they are in Korea?
There are provisions for which appointment itself is the test, so it is safer not to treat residence as a defence. We would suggest reconciling the register of directors against who is actually involved in the business.
Q2. If we pay the tax in full later, does that not dispose of the criminal process?
Payment is an important variable. For withholding tax, relief is available where payment is made before the due date for the quarterly statement. Payment after that date stands on a different footing.
Q3. We have engaged a local accounting firm. Are the officers still liable?
Outsourcing the work and changing who is bound by the statute are two different things. Confirming from the engagement letter what is absent from the scope is closer to a practical defence.
Q4. If all the directors are Indian nationals, are our own officers safe?
Reducing the number of appointments is not the same as stepping back from oversight. We would suggest composing the board so as to meet the statutory requirements, and designing the reporting line separately.
In Closing
Compliance is heavy going in India not because the amounts are large. It is heavy because, beyond a certain point, the character of the problem changes from a cost to the company into a matter of personal record for an individual.
That point cannot be moved once something has gone wrong. It was fixed on the day the tax was deducted, the day the deadline passed, and the day a name went onto the register of directors.
Put the other way round, there is still something you can do now. Establishing who is on the register, and what they are told, costs nothing today.
In the next article we will divide the purpose of entering India into four strands, and look at how the design changes with the purpose.
📘 If You Would Like to Go Deeper into This Subject
A list of the provisions that carry personal liability — items scattered across tax, company and factories legislation, gathered onto one page
What to check before a name goes on the register — what the appointee must be told, and how to structure a defence
The order of work when a withholding failure comes to light — what to stop first and what to regularise afterwards
Designating a factory Occupier in practice — whom to name and what may be delegated
📗 India Incorporation and Foreign Direct Investment (FDI) Regulation, the first volume of The Real Rules of Entering India, is available from BOOKK.
https://bookk.co.kr/bookStore/6a86df65b1468f4a36f5a612
If You Are Unsure Where to Begin with Your Entry into India
Adullam Consulting established its Indian subsidiary in Delhi in 2017 and now works from four offices — Delhi, Bengaluru, Chennai and Seoul. We have advised more than 100 companies and handled more than 300 licensing and government-facing matters.
Incorporation, tax and accounting, certification and incentives, human resources and legal, real estate, and distribution and marketing: six areas supported by a single team. Adullam Consulting will be with you as a dependable partner in your entry into the Indian market.