Hello, this is Adullam Consulting (formerly ADL Consulting).
"Let us get the revenue moving first. We will sort the administration out in one go once the company has found its feet." It is a plan we hear often from companies that have just incorporated in India. Speed of execution is a genuine strength of Korean companies, and it is not one we would ask you to give up.
There is, however, an assumption buried in that plan. It assumes that filings left undone can be caught up later, and that a single fine at that point closes the matter. In Korea the assumption is broadly sound.
India compliance does not rest on it. A penalty in India is less a sum you pay once than a balance that grows from the day the deadline passes. What follows sets out why the structure differs, and what you should be counting from which date.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
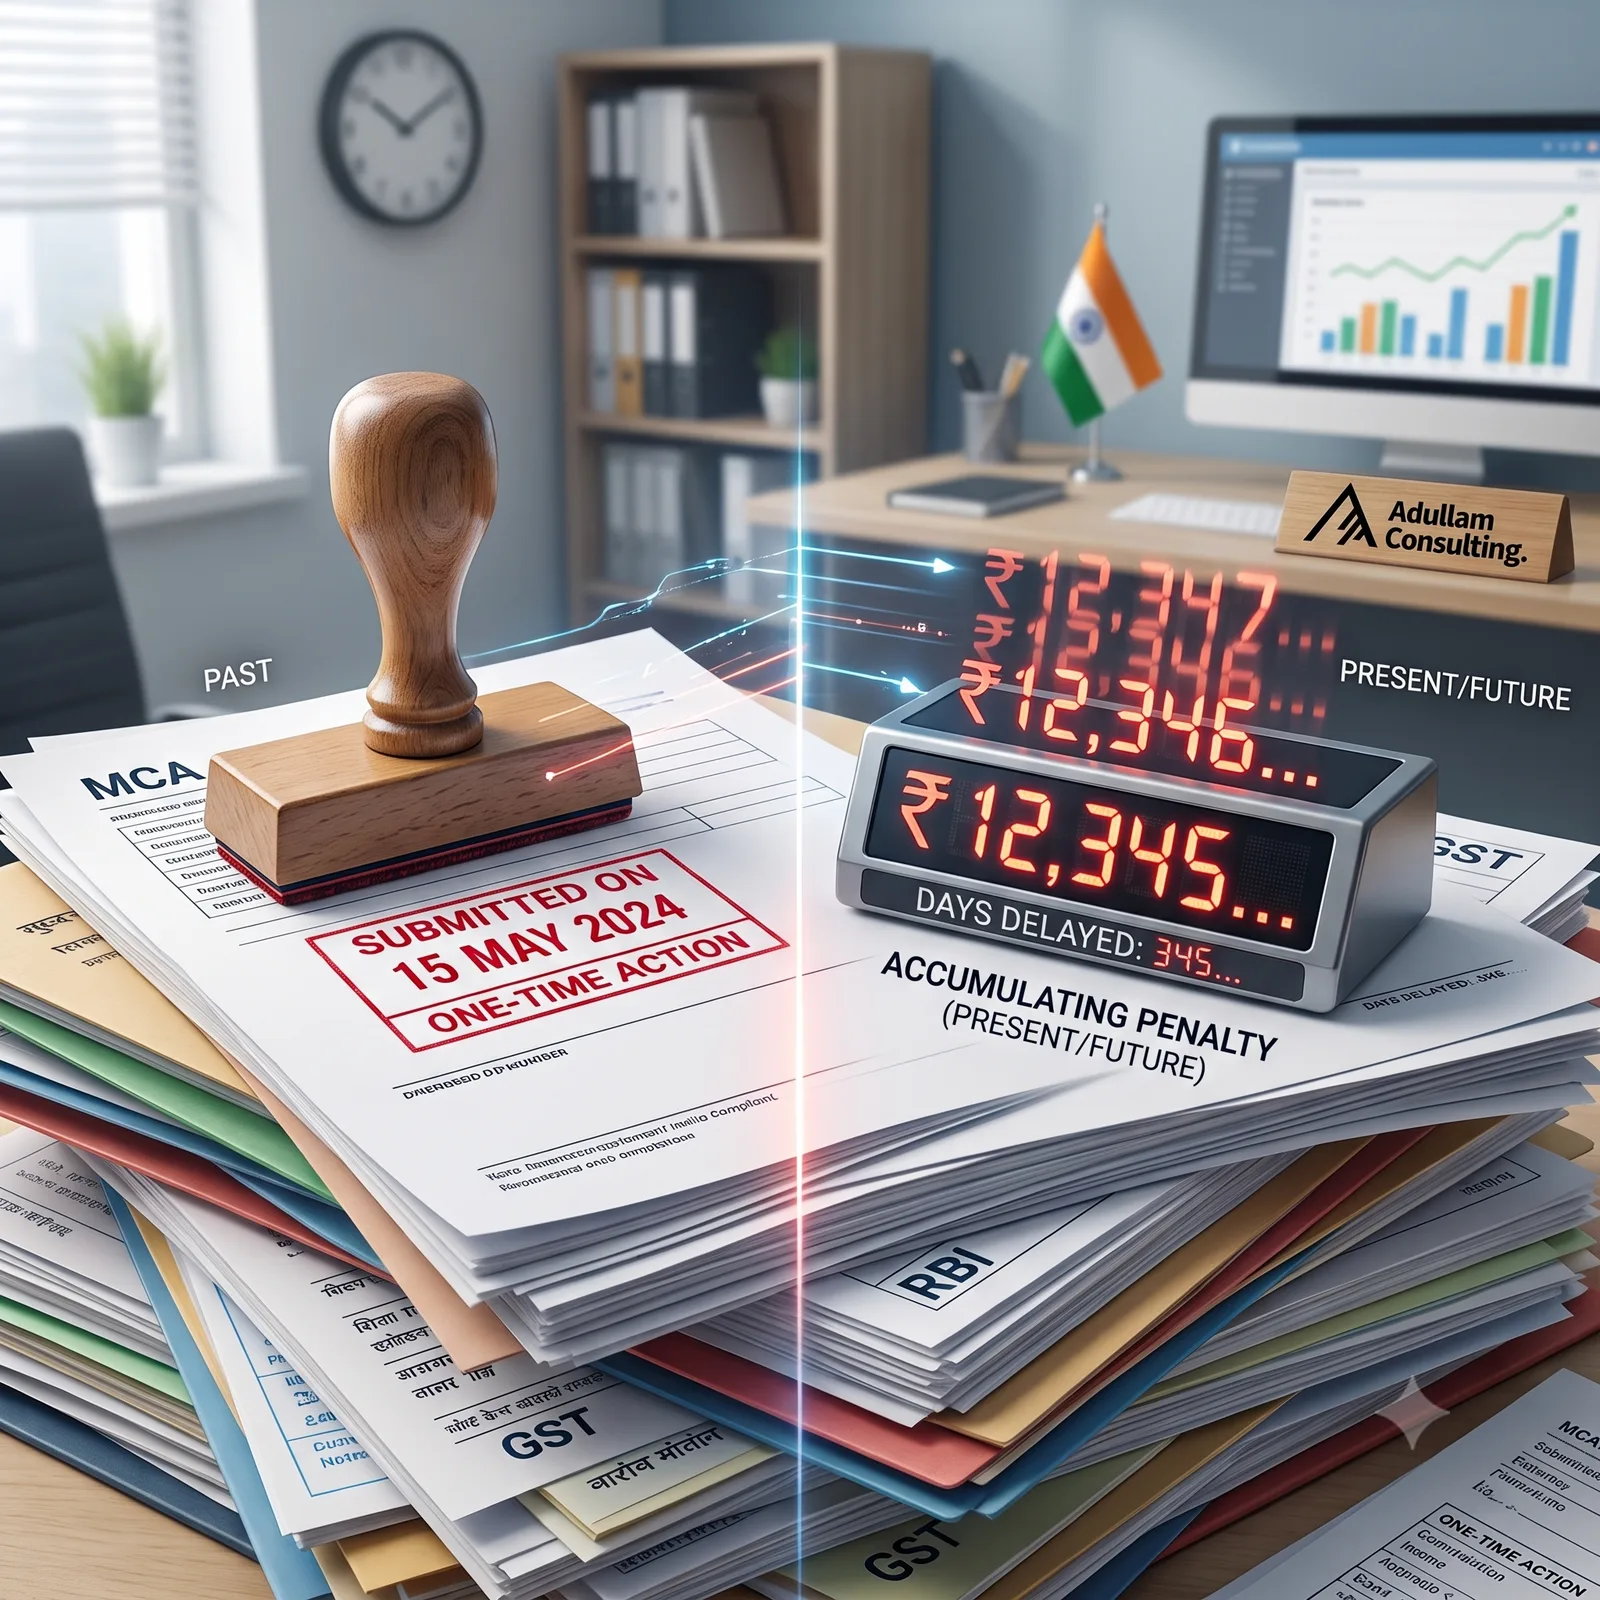
A penalty in India is not a one-off fine. For a great many filings it grows in proportion to time.
Some items carry no cap. ₹100 a day is a small figure, but nothing stops it.
An omission is counted from the day it arises, not the day it is found. The date of detection does not set the amount.
The root of the problem is not money but a list. Very few companies hold a list of their first-year filing obligations.
The gap widens in a year of heavy amendment — between a company that configures compliance once and a company that refreshes it every quarter.
1. The Two Regimes Are Built on Different Arithmetic
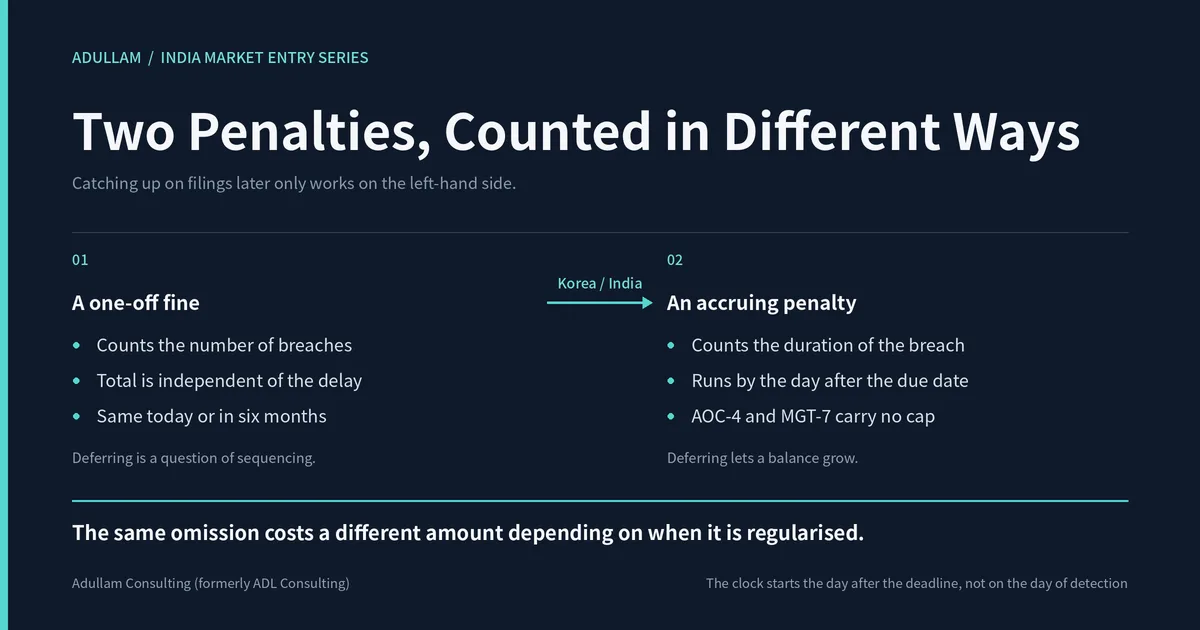
For a policy of catching up on filings later to make sense, one condition has to hold: the total penalty must be independent of how long the delay ran. Only if the amount due is the same whether you settle today or in six months' time does it become rational to deal with urgent matters first and leave the administration until afterwards.
Indian statutory filings are not built that way. A great many of them carry a charge that accrues by the day from the moment the due date passes. The delay itself is close to being the taxable event.
The difference lies not in the size of the figure but in the method of counting. One regime counts the number of breaches. The other counts the duration of the breach.
That distinction changes the shape of the decision rather than merely its price. Where the penalty is fixed, deferring a filing is a question of sequencing work, and a company that is short of hands may quite reasonably decide to do the commercial thing first. Where the penalty runs by the day, the same deferral is a decision to let a liability accumulate on the balance sheet for as long as the deferral lasts. Two companies with identical facts, differing only in when they got round to the paperwork, end up with materially different exposure.
2. Where the Meter Starts Running in Your First Year
Take only the principal filing obligations that arise in the first year after incorporation and there are six of them. Each looks minor on its own, and they share one feature: the counting begins the moment the deadline is missed.
Filing obligation | Deadline | If late or not made | Basis |
|---|---|---|---|
INC-20A (declaration of commencement) | 180 days from incorporation | ₹50,000 on the company and ₹1,000 a day on each officer — and grounds for striking the company off the register | Companies Act, section 10A |
FC-GPR (report of foreign investment) | 30 days from allotment of shares | Late Submission Fee (LSF); a compounding route where it has been left for a long time | FEMA · RBI FIRMS |
AOC-4 (filing of financial statements) | 30 days from the AGM | ₹100 a day — no cap | Companies Act, section 137 |
MGT-7 (annual return) | 60 days from the AGM | ₹100 a day — no cap | Companies Act, section 92 |
TDS (tax deducted at source) | Ordinarily the 7th of the following month | Interest and a levy, and prosecution is available | Income-tax Act, section 276B |
GSTR-3B (monthly GST return and payment) | The 20th of the following month | Interest at 18% a year | CGST Act, section 50 |
Look at the composition of that list and you will see it is not the business of one authority. The Ministry of Corporate Affairs, the Reserve Bank of India, the income tax authorities and the GST authorities each hold their own forms and their own deadlines. A company can be diligent with one of them and empty at another.
The first entry deserves a word of its own, because its consequence is of a different order from the rest. INC-20A is the declaration that the company has commenced business, and it falls due 180 days after incorporation. Miss it and the charge on the company and its officers is only part of the matter: the failure is itself a ground on which the registrar may strike the company off. A subsidiary that has been capitalised, staffed and put to work can therefore find its existence in question over a form that nobody was told to file.
3. What "No Cap" Actually Means
The entry in that table which deserves the most attention is not the largest figure. It is the words no cap set beside AOC-4 and MGT-7.
₹100 a day is not, in itself, a burdensome amount. The difficulty is that there is no point at which it stops. Where both forms are outstanding together, ₹200 accrues each day; carried across a full year that is ₹36,500 per form, or ₹73,000 for the pair. Two years is twice that.
More important than the size of the sum is that there is nothing left to negotiate. Where a fine is reduced at the discretion of an officer, there is a place to explain your circumstances. Where the figure is arrived at by counting days, there is no such place.
TDS and GST carry a further characteristic. Both are money the company has collected from another party and holds for the exchequer. When they run late the consequence does not stop at interest; the matter moves into territory in which a criminal process is provided for. The personal criminal liability of directors is a subject we will take separately in its own article.
Note — the deadlines and levels of penalty above change as the relevant legislation is amended. At the point of an actual review you should re-confirm them against the latest notification and local advice.
4. An Omission Is Counted from the Day It Arises
This is where practice most often departs from expectation. Companies assume that the reckoning starts on the day the point is raised with them.
The clock does not start on the date of detection. It starts on the day after the deadline. If a form missed three years ago comes to light this year, what the company faces is not this year's figure but three years of it. A record of diligent operation since does not stand as a defence.
For that reason the first thing we suggest in a consultation is a single request.
Show me, on one page, the statutory filings our Indian subsidiary owes this quarter.
If that one page does not arrive within a day, the figure is not the thing to worry about first. The absence of the list is. A local accounting firm performs the scope it has been engaged for, and a head office finds it hard to know what it ought to be engaging for. Omissions arise, as a rule, in the gap between the two.
It is worth being precise about why the gap opens, because it is not usually a failure of diligence on anybody's part. An engagement is written at incorporation, when the company has no employees, no imports and no turnover. Obligations then arrive as the business grows — the first payroll, the first remittance abroad, the first allotment of shares to the parent — and each of them belongs to a different authority and often to a different adviser. Nobody is asked to revise the engagement letter, so the new obligations sit outside everybody's scope while remaining squarely inside the company's.
5. The Gap Widens in a Year of Heavy Amendment
There is a further reason to hold India compliance as a standing function rather than a one-off configuration. The rules themselves change often, and substantially.
Date | What changed |
|---|---|
22 September 2025 | The move to GST 2.0 — the 12% and 28% slabs removed, leaving a two-rate structure of 5% and 18% with a 40% special rate above it |
21 November 2025 | The four labour codes brought into force |
1 April 2026 | The new Income-tax Act, 2025 in force |
8 May 2026 | Central rules under the labour codes notified |
Less than three weeks separated the GST Council's decision on GST 2.0 from the day it took effect. When rate slabs move, invoice formats, system configuration and input credit treatment all have to move with them. In a year in which amendments of that kind arrive one after another and with little runway, the distance grows between a company that treats compliance as a cost item configured once at incorporation and a company that treats it as a function refreshed every quarter.
6. What We Would Therefore Recommend
The practical guidance reduces to three lines.
First, build the list before anything else. Eliminating the gaps matters more than reducing the amounts. Four columns will do: form, deadline, owner, and the section it rests on.
Second, put the deadlines in a calendar. Monthly and annual items sit side by side, so a quarterly review on its own will miss the 7th and the 20th of the following month.
Third, check for amendments every quarter. Whether last year's procedure is still this year's procedure is a separate thing to verify, and it is not verified by the fact that last year's filing was accepted.
None of this asks for a compliance department. For most subsidiaries of the size we advise, the work is a named person in the head office who owns the list, a quarterly half-hour to reconcile it against what the local advisers have actually filed, and a standing instruction that any new activity in India is checked against the list before it begins rather than afterwards.
Frequently Asked Questions (FAQ)
Q1. Does a company with no revenue yet still have filing obligations?
It does. Annual obligations under company law such as AOC-4 and MGT-7 arise irrespective of trading results. It is not at all unusual for a company close to dormant to discover an amount that has been accumulating for several years.
Q2. We have never had anything raised with us. May we take that as reassurance?
That nothing has been raised means only that nothing has yet been looked at. It does not mean the counting has stopped. An omission accrues from the day after the deadline regardless of when it is inspected.
Q3. We have several years outstanding. Where should we begin?
The usual approach is to stop the items that are still growing each day before the items with the largest single figure. Forms that carry no cap, and heads of tax that carry interest, are what that means in practice. Deciding the order is itself the substance of the work.
Q4. Our local accounting firm handles this. What more should we check?
We would suggest confirming in writing what the engagement includes and what it leaves out. Company law forms, exchange control reporting and tax filings are distinct specialisms, and it is common for no single firm to be carrying all of them.
In Closing
India compliance is demanding not because the rules are unusually complicated. It is demanding because the cost of deferral is calculated differently from the way it is calculated in Korea.
In Korea, putting administration to one side is a judgement about the order in which work is done. In India the same judgement is a decision to let a balance grow. The character of the decision is not the same.
Put the other way round, this is an area that becomes more expensive the later you begin, and the cheapest item on the list if you begin early. Meeting a deadline costs nothing extra.
In the next article we will take the part of this field that is designed not as an administrative penalty but as the personal criminal liability of a company's officers.
📘 If You Would Like to Go Deeper into This Subject
A full map of first-year compliance — obligations scattered across authorities, gathered onto one page
A monthly master calendar — monthly, quarterly and annual items laid out across the year
The order of work when an omission is found — what to stop first and what to regularise afterwards
A scope-of-engagement checklist — the items most often absent from a local accounting engagement
📗 India Incorporation and Foreign Direct Investment (FDI) Regulation, the first volume of The Real Rules of Entering India, is available from BOOKK.
https://bookk.co.kr/bookStore/6a86df65b1468f4a36f5a612
If You Are Unsure Where to Begin with Your Entry into India
Adullam Consulting established its Indian subsidiary in Delhi in 2017 and now works from four offices — Delhi, Bengaluru, Chennai and Seoul. We have advised more than 100 companies and handled more than 300 licensing and government-facing matters.
Incorporation, tax and accounting, certification and incentives, human resources and legal, real estate, and distribution and marketing: six areas supported by a single team. Adullam Consulting will be with you as a dependable partner in your entry into the Indian market.