Hello, this is Adullam Consulting (formerly ADL Consulting).
"We have found a good local partner. We intend to split the equity down the middle." It is a sentence we hear often. A partner may bring a great deal — a distribution network, licensing contacts, land, language. An Indian joint venture is rarely the wrong choice in itself.
Our concern lies elsewhere. Where the structure of a partnership is replaced by trust in a person, that trust is tested first at the moment the business begins to do well.
The argument that a joint venture "shares the risk" is only half right. Damage to your brand, a compliance failure in the local company, and the control of transferred technology are not halved when your shareholding is halved. What a joint venture divides with any certainty is the power to decide.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
What a joint venture divides is not risk but decision-making power.
Indian company law sets two thresholds — a simple majority and 75%. That is what makes 26% a blocking stake.
A 50:50 does not break when the business goes badly. It breaks when the business goes well.
A shareholders agreement binds the company only once it is written into the articles.
A put option that guarantees your money back does not exist in India.
1. The Grammar of Shareholding — 26, 51 and 76
If control is being bought and paid for in equity, you had better be able to read the price list. Section 114 of the Companies Act, 2013 divides shareholder resolutions into two kinds. An ordinary resolution passes when the votes in favour exceed the votes against. A special resolution passes when the votes in favour are not less than three times the votes against. Converted into a percentage, that is the 75% the market talks about.
What most companies miss is the denominator. The 75% is measured not against the total issued share capital but against the votes actually cast at that meeting. A 26% stake is indeed a blocking stake, but it is a shield only on the days its holder attends and votes against. A minority that stays away in the hope of frustrating a meeting achieves the opposite: the quorum rules allow a reconvened meeting to proceed on the members present, and the absent shareholder has thrown away the very veto it paid for. Defending a minority position therefore takes more than a percentage — it takes a reliable route for notices to reach you, a standing proxy, and the reserved matters written into the articles.
Shareholding | What it secures | What it does not |
|---|---|---|
76% and above | Special resolutions alone — amending the articles, capital reduction, restructuring | A merger still needs NCLT sanction and a creditors' process |
51–75% | Appointment and removal of directors, a board majority, day-to-day management | Amending the articles, capital reduction, mergers |
Exactly 50% | Effectively nothing — a tie is a defeat | Not even an ordinary resolution can be carried alone |
26–49% | A veto over special resolutions; standing to seek minority relief | A board majority; decisions on dividends |
Below 26% | With 10% or more, the right to requisition a general meeting | Any blocking power — rights then come from the articles |
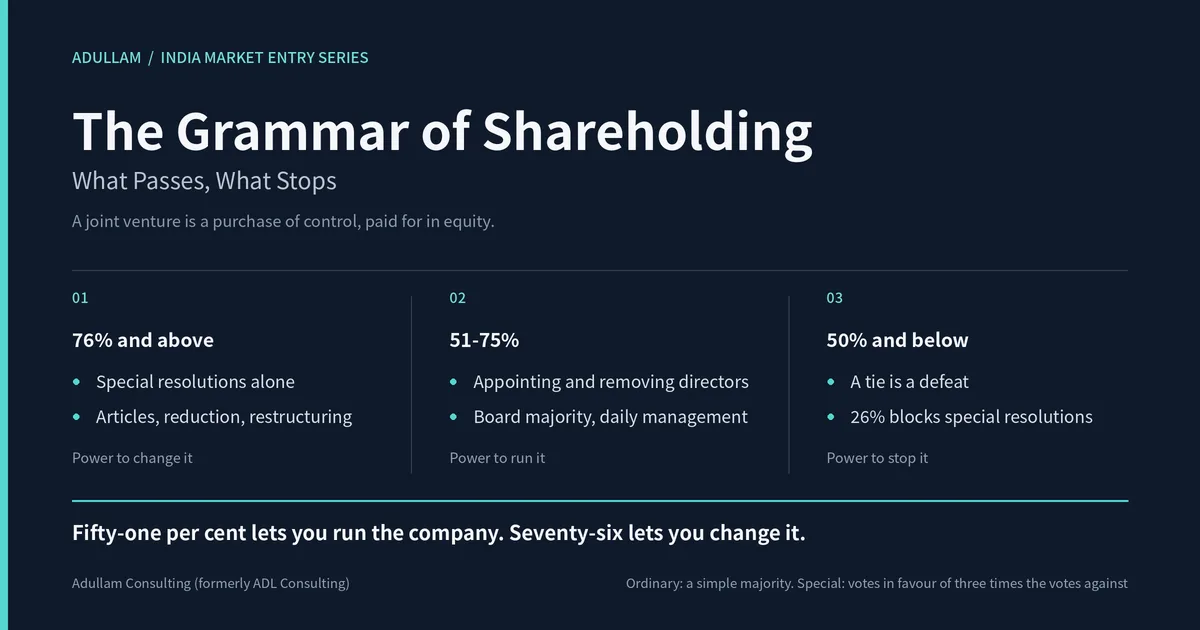
We would encourage you to set your negotiating target at 76%, not 75%. The three-to-one rule bites at exactly 3:1, and the two extra points remove the room for rounding, nominee holdings or option dilution to take you below the line. Conversely, where an Indian partner insists on precisely 26%, read it as a statement of intent: they are buying a veto, not a dividend.
2. A 50:50 Breaks When the Business Goes Well
Offered as a gesture of goodwill, a 50:50 is the most expensive symbol in the field. Even an ordinary resolution requires the votes in favour to exceed those against, so a tie is a defeat, and the board splits two to two. The result is not balance. It is a standstill.
The timing deserves attention as well. The more a company grows, the more decisions it has to take, and the more decisions it takes, the more often it comes to a halt.
The automotive components case set out in our book follows that path exactly. The venture began 50:50 and ran smoothly for three years. When an expansion became necessary, the partner would neither subscribe nor accept dilution. A preferential allotment is a special resolution, so at 50% it could not even be tabled; when the Korean side tried to route the money through a parent-company loan instead, the board vote stood at two to two. Fifty-one per cent lets you run the company. It does not let you change it.
3. Partner Due Diligence — Half of It Is Free and Public
Korean due diligence tends to begin with audited accounts and end with audited accounts. In India a great deal of it is settled in public databases that need no login at all. The cost is close to nothing.
What to check | What it tells you |
|---|---|
Directorships held | Search by Director Identification Number (DIN) — how many struck-off, dormant or wound-up companies sit behind your counterparty |
Charges created and satisfied | Old charges registered but never satisfied; any pledge over the shares or the funds to be subscribed |
Pending litigation | Oppression and mismanagement petitions against former joint venture partners |
Annual filings and GST | Habitual delay and penalty history; filing discipline where a group company will supply the venture |
Look for what the documents do not say, too. Set three years of related-party notes side by side: where a material share of sales or purchases runs through companies owned by the promoter family, assume the venture will be handled the same way and design your reserved matters accordingly. Shareholdings in Indian mid-sized groups are commonly spread across individuals, family trusts, a Hindu Undivided Family and holding companies, so the promoter family's structure and succession plan belong on the list as well; a joint venture usually outlives the health of one promoter, or the goodwill between brothers.
One suggestion we would add. Meet the partner's finance head and plant manager on their own, without the promoter in the room. Where the company the promoter describes and the company the managers describe are not the same company, the managers are right. What you are examining is not a company but a person, and the filing history shows you the habits that the accounts do not.
※ Note — India's corporate filing portal was consolidated in June 2025. Search routes and forms may change, and you should re-confirm them at the time of your review.
4. A Shareholders Agreement Has to Be Written into the Articles
Here lies the structural mistake Korean companies make most often in Indian joint ventures: the belief that a well-drafted shareholders agreement is enough.
Under Indian law a shareholders agreement is a private contract binding only its signatories. In V.B. Rangaraj (1991) the Supreme Court held that a restriction on the transfer of shares that had not been incorporated into the articles could not bind the company; in Vodafone (2012) it took the view that clauses such as tag-along do bind the contracting parties even where the articles are silent.
The practitioner's answer is still the same: put them in. Where a partner transfers shares in breach of the agreement, what allows the company to refuse to register the transfer is the articles — and where the two documents conflict, the articles win.
Four devices are the minimum that must be carried across: reserved matters (capital increases, borrowing, dividends, senior appointments), deadlock resolution (through to call and put options and a sale to a third party), transfer restrictions (rights of first refusal, tag-along and drag-along rights), and exit design (the pricing formula and the procedure).
Timing decides the outcome. Amending the articles is itself a special resolution, so if completion of that amendment is not a condition precedent to closing, there is no remedy left once a counterparty holding more than 25% declines to co-operate.
5. Exit — There Is No "Money-Back" Put in India
The sentence that carries an Indian investment through a Korean board paper usually appears at this point. "We have secured a put option returning our principal plus 8% a year after five years." That sentence does not hold in India.
Under the non-debt instruments framework, an investment carrying an option is permitted on three conditions: a minimum lock-in of one year, no assured return, and a sale price that does not exceed fair market value at the time of exercise. A non-resident leaves at the price formed on the day of exit, not the price agreed on the day of entry.
That does not leave you without options. First, build the formula inside the fair-value ceiling and control the valuation itself by contract. The price of unlisted shares in India must be certified by a chartered accountant or a registered merchant banker, so pinning down the methodology and the procedure for appointing the valuer is, in substance, control of the price.
Second, secure the economics through damages for breach of an obligation rather than through the price. In the NTT Docomo and Tata Sons matter, an LCIA tribunal ordered payment of roughly US$1.17bn in 2016 and the Delhi High Court allowed enforcement in India in 2017. What proved decisive was that the award was framed not as performance of a share sale above fair value but as damages for breach of a contractual obligation.
Design the other exits alongside the put, not after it: a sale to a third party consistent with your drag, tag and pre-emption rights; a qualifying listing, with the definition, the deadline and the fallback if it is missed; a buy-back or capital reduction by the company; and, last of all, liquidation. Each route carries a different regulatory process and a different tax result, so the comparison that matters is the after-tax amount in your hands on the day of recovery.
Putting the seat of arbitration outside India is a reasonable choice, but it is not a firewall. Claims of oppression and mismanagement are not arbitrable, so your partner can still go to the National Company Law Tribunal — where the backlog stood at roughly 30,600 cases as at March 2025. One line in the standard international form deserves a second look as well: an exclusion of Part I of the Arbitration and Conciliation Act, 1996 also closes off the route to an Indian court for interim relief, which is often the fastest way to stop shares being transferred or assets being moved.
Frequently Asked Questions (FAQ)
Q1. Can we go in at 100% without a partner at all?
Where the FDI cap for your sector is 100% and the automatic route applies, a wholly owned subsidiary is the default. The reasons to give up equity come down to a statutory sectoral cap, land and industrial plots, government procurement requirements, and a distribution or after-sales network.
Q2. If we hold 51%, is control not secure?
Fifty-one per cent gives you a board majority and day-to-day management. It does not give you amendments to the articles, preferential allotments, capital reduction or mergers. We would suggest counting how many special resolutions sit in the next five years of your own plan.
Q3. We have already incorporated on a 50:50 basis. Is there anything we can do now?
While relations are good is the only window you have. An amendment to the articles is a special resolution and needs both sides, and once a dispute has begun that consent becomes a bargaining chip.
Q4. We understand minority shareholders have a remedy. Is that not enough?
The oppression and mismanagement remedy exists, and it extends as far as an order to buy out your shares. The difficulty is not standing but time. Designing a shareholding structure around it is the logic of keeping no fire extinguisher because the building is insured.
In Closing
A partner acting in bad faith is rarer than you would expect. With even the best of partners a moment arrives when interests diverge, and what governs that moment is not the relationship but the documents.
The object of the design, then, is not a structure that wins a dispute but a structure that does not stop when one arises. In India the real cost of a dispute is not the outcome but the duration, and every remedy we have described — minority relief, arbitration, enforcement — works on a timescale that a business does not have.
Asking for reserved matters and a deadlock procedure is not an expression of distrust. Settle in advance what will be done if there is a disagreement, and the disagreement does not go so far as to break the relationship.
📘 If You Would Like to Go Deeper into This Subject
The full shareholding table — what each band permits and what it blocks
Five written questions before a joint venture decision — what your board should answer first
Reading the poison clauses in a shareholders agreement — drag-along, anti-dilution, deadlock, non-compete and exit
Mapping the agreement against the articles — how to find the clauses with no counterpart
📗 Volume 1, India Incorporation and Foreign Direct Investment (FDI) Regulation, of The Real Rules of Entering India is available from BOOKK.
https://bookk.co.kr/bookStore/6a86df65b1468f4a36f5a612
If You Are Unsure Where to Begin with Your Entry into India
Since establishing a local subsidiary in Delhi in 2017, Adullam Consulting has operated from four locations — Delhi, Bengaluru, Chennai and Seoul — advising more than 100 companies and handling more than 300 licensing and government liaison matters.
We support six areas from a single team: incorporation, tax and accounting, certification and incentives, human resources and legal, real estate, and distribution and marketing. Adullam Consulting will be with you as a dependable partner in your entry into the Indian market.