Hello, this is Adullam Consulting (formerly ADL Consulting).
"How many Korean companies that have entered India can be called successful?" It is the question we are asked most often — which is another way of asking how common failure in an Indian entry really is.
The honest answer is that nobody knows. The statistical base is so thin that even the number of Korean companies operating in India was not established until 2025, when KOTRA and the Korea International Trade Association carried out the first full census with the support of the Embassy of the Republic of Korea in India. No success rate exists.
What we watch is not the volume of failure but its distribution. Companies that share neither sector nor scale come to grief in remarkably similar places.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
This is not a Korean phenomenon. Between 2014 and November 2021, 2,783 foreign companies and their subsidiaries wound up their operations in India.
Companies do not fall over for want of capital or talent. Ford, General Motors and POSCO are on that list.
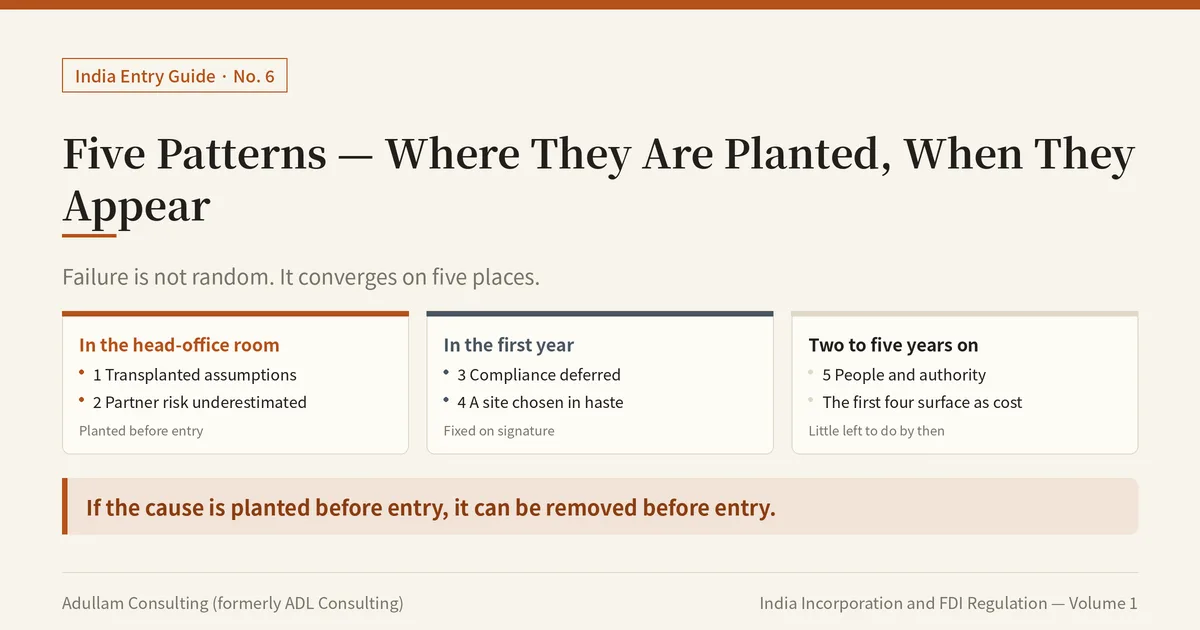
Failure is not randomly distributed. In our records, it converges on five places.
All five are planted before entry, or in the first year. They simply take two to five years to present themselves.
This is therefore not bad news. What is planted before entry can be removed before entry.
1. The Numbers First — A Market with Both Doors Wide Open
According to the written reply the Ministry of Commerce and Industry gave the Lok Sabha in December 2021, 2,783 foreign companies and their subsidiaries closed their operations in India between 2014 and November 2021. That is roughly one a day. With 12,458 foreign subsidiaries active at the same date, about one in five had left. A further parliamentary paper in February 2023 put the number of foreign companies and subsidiaries closed between 2017 and 2022 at 3,552.
The macro figures point the same way. Gross foreign direct investment into India in FY2024-25 came to US$81bn, up 13.7% on the year before. Net FDI for the same year, however, was no more than about US$0.4bn on the figures first published. Repatriation and disinvestment by existing foreign investors reached US$51.5bn, a record at the time, and outward investment by Indian companies added a further US$29.2bn.
The Reserve Bank of India described this as the mark of a mature market in which investors are free to come and go. That is fair comment. Read from a company's side of the table, however, it says something else: India is a market in which tens of billions of dollars walk in and tens of billions walk out in the same year. In FY2025-26 gross inflows reached an all-time high of US$95bn and net FDI recovered to US$7.65bn, but repatriation set another record at US$53.6bn. The structure — large flows in both directions — has not changed.
We put these figures first for one reason. It is not that India is a dangerous market. It is that coming to grief there is not an exceptional event, and a board that treats it as one will not look for the causes in its own plan.
2. Failure Happens in the Same Places — The Five Patterns
Set ten years of advisory files side by side and the ground converges on five places.
Pattern | Typical symptoms |
|---|---|
① Transplanted home-market assumptions | Entry vehicle, contracts and timetable designed "as we do it in Korea" |
② Partner risk underestimated | A joint venture begun on trust, without a shareholding structure or a shareholders agreement |
③ Compliance deferred | "Revenue first, filings later" — omissions return years later as penalties |
④ A site chosen in haste | State and plot settled on logistics distance and an introduction |
⑤ People and authority | A three-year expatriate rotation and a local organisation with no power to decide |
3. Patterns ① and ② — Assumptions Carried Over, Partnerships Without Documents
The commonest pattern is complete before anyone lands in India. It is finished in a meeting room at head office, where the premises that worked at home are carried across intact: a branch is lighter than a subsidiary, an application will be processed, a standard form of contract will do, the auditors will handle the tax filings.
An unincorporated place of business in India is not the light option. Under the RBI's Master Direction, a liaison office and a branch office are approved only after the parent's record of consecutive profitability and its net worth have been examined, and their opening, renewal and activity reporting all sit under the supervision of an authorised dealer bank and the RBI. The arithmetic of "let us start lightly with a liaison office" is nonetheless repeated every year, and it ends in the scenario this series returns to again and again: staff of a liaison office found to be carrying on commercial activity, and a permanent establishment assessment reaching back to the parent's own turnover.
The largest companies in the world were not exempt. Ford invested roughly US$2.5bn over the twenty-five years following its re-entry and never moved much beyond a 2% share, and in September 2021 it announced that it would stop production, carrying more than US$2bn of accumulated operating losses from the preceding decade. General Motors had already withdrawn from the domestic market in 2017 on a share of under 1%.
What happened next is the instructive part. The Sanand plant Ford left has been taken over by Tata Motors and turned to electric vehicles; GM's Talegaon plant was acquired by Hyundai Motor, which completed the purchase in January 2024 and brought it into operation the following year. In the same country, on the same plot of land, a different company makes money. The problem was not India. It was the design.
The second pattern is the partner. A local businessman is met at a trade fair; the shareholding is set at 50:50 as a mark of goodwill; the shareholders agreement (SHA) is left out because "the legal fees are a waste and it would put a crack in the relationship". The first two years go smoothly. The break comes when the business begins to do well. The partner declines to subscribe at a rights issue and refuses to be diluted, the board deadlocks two against two, and the bank mandate and the keys to the plant are on the other side. Only then does head office discover that it has been a minority shareholder holding 50%.
Scale does not alter the substance. Daiichi Sankyo acquired control of Ranbaxy in 2008 for approximately US$4.6bn and exited in 2014 by selling to Sun Pharma. In 2016 an ICC tribunal found that the sellers had concealed the existence of an internal report bearing on a United States regulatory investigation, and ordered payment of approximately ₹3,500 crore including interest and costs. The due diligence of a leading Japanese pharmaceutical company did not filter out a determined concealment. What it did have was a set of representations and warranties, and that is why an award existed at all. Had the transaction begun on trust and nothing else, there would have been no award to enforce.
4. Pattern ③ — In India the Penalty Does Not Land Once; It Grows Daily
The execution speed that is a strength of Korean companies becomes, in India, a cause of accidents. Penalties here are not one-off fines. They are cumulative, and they grow in proportion to time.
Filing obligation | Deadline | On delay or default |
|---|---|---|
INC-20A (declaration of commencement) | 180 days from incorporation | ₹50,000 on the company, ₹1,000 per day on officers; grounds for strike-off |
FC-GPR (reporting of foreign investment) | 30 days from allotment | Late Submission Fee (LSF) |
AOC-4 / MGT-7 (financial statements, annual return) | 30 / 60 days from the AGM | ₹100 per day, with no cap |
TDS remittance (withholding tax) | 7th of the following month, as a rule | Interest and levies, and exposure to prosecution |
GSTR-3B (monthly GST return) | 20th of the following month | 18% interest per annum; power of arrest above ₹5 crore |
The heavier point is that a considerable number of breaches are framed as the personal criminal liability of an officer. Where tax is withheld and not paid over to the exchequer, section 276B of the Income-tax Act puts the matter within reach of prosecution carrying a term of not less than three months and up to seven years. An amendment in 2024 introduced relief where payment is made before the due date for the quarterly statement, and that architecture has been carried into the new Income-tax Act in force from April 2026 — but it is not a mechanism for rescuing habitual delay.
The Nokia case shows the upper bound of this pattern. In January 2013, a tax investigation into the company's Chennai plant produced a demand of approximately ₹2,080 crore for failure to withhold on royalty remittances. With the assets frozen, the plant alone was carved out of Microsoft's acquisition of Nokia's handset business. Orders stopped, and in November 2014 a factory employing 8,000 people directly fell silent. It did not turn again until 2020, under Salcomp. Nobody compensated anyone for the six years in between.
The pace of regulatory change makes this pattern more dangerous still. The period this book covers alone contains the move to GST 2.0 in September 2025, the four labour codes coming into force in November 2025 with the central rules notified in May 2026, and the new Income-tax Act taking effect in April 2026. The gap between a company that treats compliance as a cost item set up once at incorporation and one that treats it as a standing function refreshed each quarter opens up precisely in a year like that.
※ Note — the deadlines and levels of penalty above change as the underlying legislation is amended. You should re-confirm them against the latest notification and local advice at the time of your review.
5. Patterns ④ and ⑤ — The Most Expensive Decision Taken Fastest, and Nobody Able to Decide
We set out the site question at length in an earlier article, so we will take only its shape here. The paradox is this: the most irreversible and the largest decision in an Indian entry — which state, which plot — passes in practice on the shortest review of any item on the list. Because the customer is close by. Because somebody made an introduction. Because the industrial estate looked tidy on a site visit.
POSCO's Odisha project is the extreme case. The memorandum signed with the state of Odisha in June 2005 — US$12bn, twelve million tonnes a year, the largest foreign direct investment in India's history at the time — did not break ground in twelve years. Land handover was held up by determined local opposition; the environmental clearance obtained in 2011 was suspended by the National Green Tribunal in March 2012; and the mining concession on which the raw material supply depended fell away when the 2015 amendment to the mining law moved allocations to auction. POSCO told the tribunal in 2016 that it would not proceed, and the project was formally closed in March 2017 when the company asked for the site to be returned.
The sequel completes the lesson. POSCO did not abandon India. It signed a US$5bn memorandum with the Adani Group at Mundra in Gujarat in January 2022, and in October 2024 a joint venture memorandum with JSW for a five-million-tonne integrated works. What changed was the method: the first attempt's formula of sole investment, greenfield land acquisition and pushing straight through was set aside in favour of a joint venture with a first-rank local partner, the use of existing industrial infrastructure, and flexibility as to location. Site risk is not a variable you solve with money and resolve. It is one you avoid before you enter.
The mid-market version differs only in scale. Before you sign a land contract, at the least the following should have been established: a thirty-year trace of the title chain, with the register, the revenue records and the survey records agreeing; an encumbrance certificate confirming the absence of mortgages, attachments and pending litigation; the conditions precedent for change of land use, zoning and environmental clearance; and the state's stamp duty and registration charges, which on a combined basis range from around 5% to 11%.
The fifth pattern is not in any statute book, and yet we have watched companies that had put the other four in order come apart on it. A three-year expatriate posting spends its first year learning India, comes good in the second, and runs out in the third on handover and repatriation. Relationships and tacit knowledge evaporate with the posting, and the successor climbs the same curve from the bottom. Counterparties and officials know the cycle precisely, and know that an unfavourable negotiation can simply be deferred until the next country head arrives.
The question of authority is more damaging still. There are subsidiaries in which the country head has no delegated authority and a trivial payment goes back to head office for approval, and organisations in which a locally hired executive is given a title but kept off the approval chain. India's market for able people is narrow and reputation travels quickly in it. More than 1,700 global capability centres on the government's own count are absorbing over 2.3 million skilled staff, and average attrition across industry stood at around 17% on a 2025 survey. The moment the view forms that "that company does not give authority to Indians", your grade in the recruitment market falls a step, and the key people you still have are the first to leave.
Frequently Asked Questions (FAQ)
Q1. We are a small company. Do these cases really apply to us?
Only the amounts differ; the structure is the same. If anything, partner disputes at smaller companies that began without documents tend to end without any recovery of the shareholding at all, because there is nothing to argue from.
Q2. We are already in India. Is there anything we can check now?
Ask for one thing: "show me this quarter's statutory filing obligations for our Indian subsidiary on a single sheet." If it does not arrive within twenty-four hours, something is most likely being missed. An omission begins accruing interest from the moment it occurs, not from the moment it is discovered.
Q3. Would it not be safer to go in alone, without a partner?
It depends on your purpose. The partner is not the problem; a partnership without structure is. Reserved matters, a deadlock resolution procedure, restrictions on transfer and a designed exit, all set down in writing, tend to help a good partnership last rather than to strain it.
Q4. With so many failures on record, should we reconsider entering India at all?
Companies have been winning in the same market for decades. The question for your board is not "is India dangerous" but "are any of these five seeds present in our own entry design".
In Closing
Set the five side by side and the common feature appears: not one of them is a failure caused by India changing the rules. Ford's product strategy was settled at the point of re-entry, Daiichi Sankyo's loss on the day the purchase agreement was drafted, and POSCO's twelve years when the memorandum was signed in 2005.
If the cause is planted before entry, it can be removed before entry. Sorting for these five seeds, before you raise your execution speed, is the cheapest insurance available to you in India.
India does not discriminate between companies by nationality. It discriminates by preparation.
In our next article we will take the second pattern on its own, and set out what actually happens in an Indian joint venture begun without a contract.
📘 If You Would Like to Go Deeper into This Subject
Self-diagnostic questions for the five patterns — the expressions in an entry plan that should be read as warnings.
The full map of first-year compliance — a month-by-month master calendar of what is due, when and from whom.
The four minimum devices in a shareholders agreement — reserved matters, deadlock resolution, transfer restrictions and exit design.
Liaison and branch office requirements under the RBI Master Direction — approval criteria and reporting duties by entry vehicle.
📗 Volume 1, India Incorporation and Foreign Direct Investment (FDI) Regulation, of The Real Rules of Entering India is available from BOOKK.
https://bookk.co.kr/bookStore/6a86df65b1468f4a36f5a612
If You Are Unsure Where to Begin with Your Entry into India
Since establishing a local subsidiary in Delhi in 2017, Adullam Consulting has operated from four locations — Delhi, Bengaluru, Chennai and Seoul — advising more than 100 companies and handling more than 300 licensing and government liaison matters.
We support six areas from a single team: incorporation, tax and accounting, certification and incentives, human resources and legal, real estate, and distribution and marketing. Adullam Consulting will be with you as a dependable partner in your entry into the Indian market.