Hello, this is ADL Consulting.
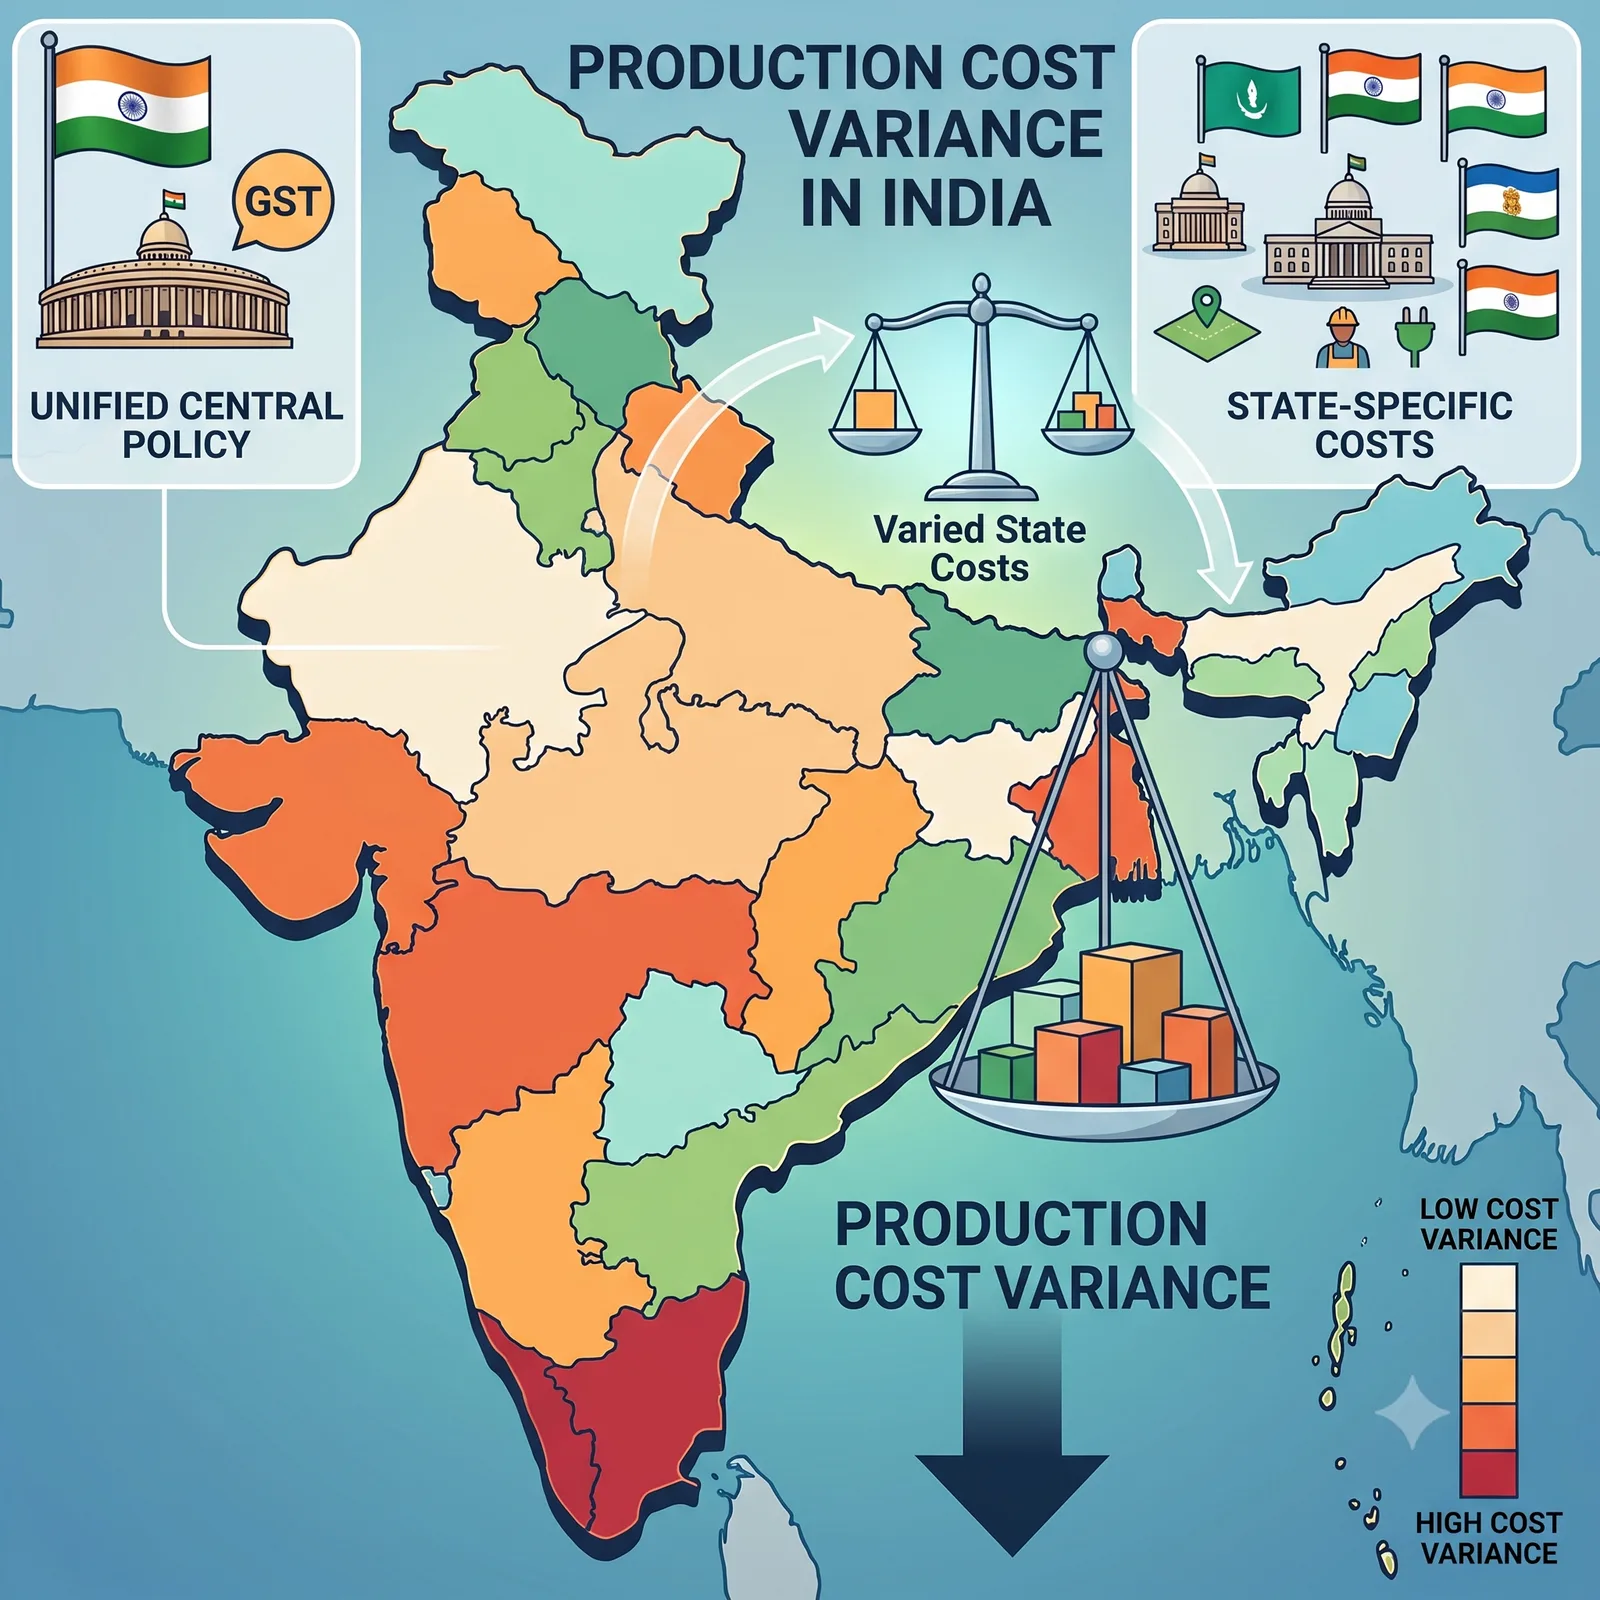
"India's GST rate is the same across the country, so surely the tax burden is the same wherever we put the plant?" This is a question we receive often from companies preparing to enter India. The first half of it is correct. The second half is not.
In our previous article we set out how far your costs diverge simply by changing state. Today we deal with why that gap arises at all.
It is not a defect in the system. It is the result of a design laid down by India's Constitution. GST did not alter that design; it is a reform that tidied up one box within the range the design permits.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
What GST unified is one thing only: the indirect tax levied on supplies of goods and services.
The boundary of that unification was drawn by the Seventh Schedule to the Constitution. Entry and capital fall to the centre, land, electricity and stamp duty to the states, and labour to the concurrent field.
GST 2.0 reduced the rates to two axes, 5% and 18%. That is progress inside the rate schedule, and no more than that.
GST has in fact intensified incentive competition between the states. Once the states could no longer cut the rate, SGST reimbursement became the detour.
The language of sales is common to the whole country; the language of production is a state-by-state dialect.
1. What India's GST Demolished — the Customs Barriers at State Borders
Before GST came into force on 1 July 2017, India was a country in which Central Sales Tax (CST), state VAT, Entry Tax and Octroi were layered on top of one another every time goods crossed a state border — in effect, twenty-eight customs barriers. GST demolished those barriers.
On 3 September 2025 the 56th meeting of the GST Council resolved upon what is known as 'GST 2.0', which took effect on the 22nd of the same month and restructured the multi-slab arrangement of 0, 5, 12, 18 and 28% into two axes of 5% and 18%.
Both reforms, however, are events that took place inside the rate schedule. Neither of them touched what lies outside it. The rate you charge on a supply became simpler and more predictable; the cost of producing the thing you are supplying was left exactly where it was. That distinction is the whole of this article, and it is worth holding on to before we go any further.
2. The Boundary of Unification — the Line Drawn by the Seventh Schedule
India is a federal state made up of 28 states and 8 union territories. The decisive fact for your purposes is that the Seventh Schedule to the Constitution divides legislative competence into three lists: Union, State and Concurrent.
The form of your entry and the regulation of capital — FDI and FEMA — are matters for the centre, and they are therefore identical wherever in India you go. The operational field, by contrast — land, labour, electricity, licensing and incentives — lies almost entirely in the hands of the state governments.
Incorporating a company is something you do with India. Running a business is something you do with a state.
Field | Uniform nationwide (centre) | Differs by state |
|---|---|---|
Entry and capital | FDI and FEMA, incorporation procedure (SPICe+) | Not applicable |
Taxation | GST rates and HSN classification, corporate tax rate, customs duty | Stamp duty, professional tax, electricity duty, SGST reimbursement |
Labour | The four Labour Codes themselves, EPF and ESIC | State rules, prior approval threshold for retrenchment |
Production base | Environmental legislation and the Factories Act themselves | Allotment of industrial land, CTE/CTO, electricity tariffs |
Incentives | Central PLI and ECMS | Capital subsidy, interest subsidy, exemption from stamp duty |
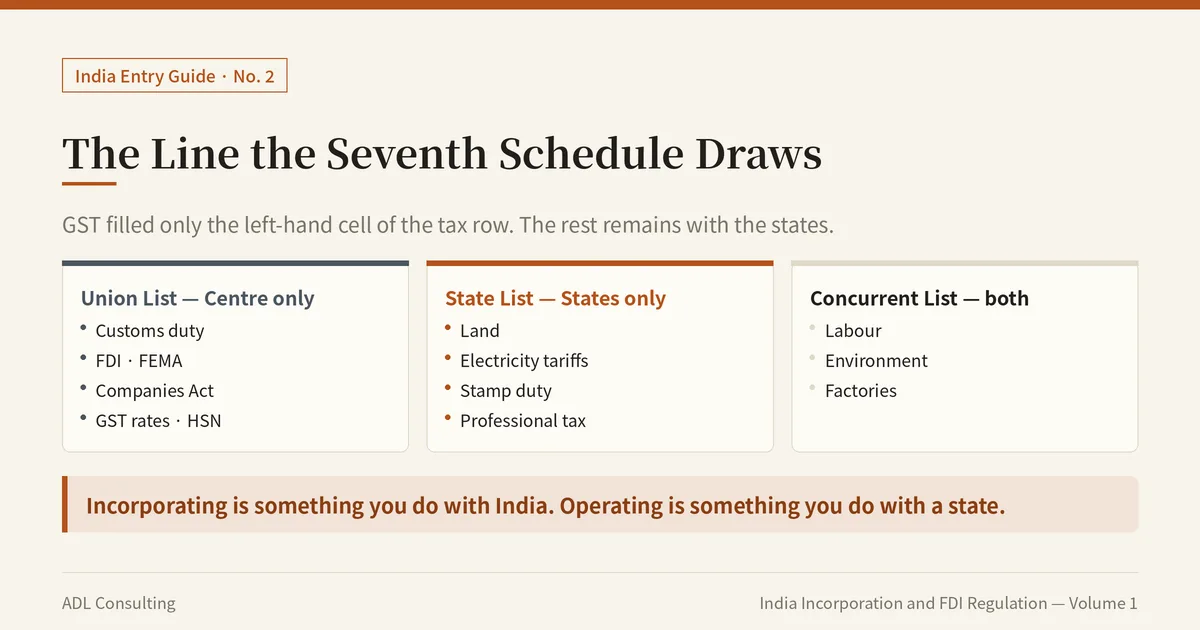
The left-hand column is territory your head office needs to examine only once. The right-hand column is territory you must go back over every time you change state. GST filled in the left-hand cell of the taxation row, and that cell alone.
3. The Paradox — Once the Rate Could No Longer Be Cut, the Incentives Grew
The introduction of GST did not soften incentive competition between the states. It sharpened it.
Previously a state government could waive VAT and thereby cut the tax itself. Now that the rate is uniform nationwide, it no longer has that power.
The detour that emerged is Net SGST Reimbursement: the state's share of the GST you have paid is returned to you afterwards in the form of a subsidy. It is typically designed at 75–100% over a period of 7 to 15 years, and is put to you bundled together with a capital subsidy and an interest subsidy.
Item | Before GST | After GST |
|---|---|---|
Power to set the rate | The state adjusted VAT relief | Uniform nationwide; the state has no such power |
Instrument for attracting investment | Cutting the tax | Returning it after payment (SGST reimbursement) |
What you need to check | That state's rate schedule | That state's incentive policy and its application requirements |
Result | The rate itself differed from state to state | The rate is the same, but the effective burden differs |
The last line of that table is the title of this article.
There is a further difference between the two columns, and it is the one that costs companies money. Relief under the old arrangement applied automatically. An incentive today is something you must apply for, and most states impose prior registration as a condition of doing so.
4. The Same Structure Repeats Once More in Labour
On 21 November 2025 India's four Labour Codes — on wages, industrial relations, social security, and occupational safety and health — came into force, consolidating some twenty-nine central labour statutes into four. The central rules were then notified on 8 May 2026.
It is easy, on reading that, for a head office to conclude that Indian labour matters can now be managed under a single standard policy.
That is the same misunderstanding as the one made over GST. Labour sits on the Concurrent List. The rules that actually bind a company — working hours, forms, registration procedures, penalties — take effect only once each state has notified them for itself. As at August 2026, Maharashtra, Gujarat and Karnataka, among others, had completed their final notifications, whereas Tamil Nadu had notified only in part. The same sentence — "the codes are in force" — therefore describes two quite different working environments depending on which state you are standing in.
The item that carries the greatest weight here is the threshold for prior approval of retrenchment. The old Industrial Disputes Act of 1947 set that threshold at 100 employees; section 77 of the new Industrial Relations Code raised it to 300. How warmly that figure is applied on the ground, however, still depends on how far the state in question has progressed with its own notifications.
5. Moving the Unit of Review from 'India' to 'the State'
Everything set out above reduces to a single sentence. GST guarantees that "the tax rate is the same wherever in India you sell". It does not guarantee that "the cost is the same wherever in India you manufacture".
If your purpose is domestic sales, you will enjoy the benefit of GST unification in full. If, on the other hand, you are establishing a manufacturing base, GST is one of several dozen variables to be examined alongside electricity, stamp duty, labour and incentives.
In practice we would recommend the following order: settle your purpose in entering India first; narrow the field to the five or six states that fit that purpose; then compress it to three and submit the same investment proposal to all three at the same time. Submitting the same proposal matters as much as submitting it to three parties, because it is what allows the replies to be compared line by line rather than read one after another. Having more than one state on the table is not a tactic within the negotiation. It is the substance of the negotiation.
Frequently Asked Questions (FAQ)
Q1. If the GST rate is identical across India, why does the tax burden still differ from state to state?
A. What differs are the items that sit outside GST. Stamp duty, professional tax and electricity duty are matters within the competence of the states under the Constitution, and SGST reimbursement is then added on top of them. It is the combination of these that causes the effective burden to diverge.
Q2. Does state selection matter for a company that only sells domestically?
A. Less than it does for a manufacturing base, but it is not irrelevant. Whether you incur a professional tax registration obligation depends on the state in which you place your establishment, and if a warehouse or branch is later opened in another state you will need to check that state's rules as well.
Q3. If we invest in a state, do we receive SGST reimbursement automatically?
A. No, it is not automatic. Most states impose prior registration before the investment commences as a condition, and if you miss it the core items are excluded.
Q4. The four Labour Codes are in force, so surely labour is now uniform across the country?
A. The codes themselves are uniform; the rules are not. The rules take effect only once each state has notified them. We would recommend checking the notification status of each state on your shortlist individually.
In Closing
GST unified the tax rate on sales; it did not unify the cost of production. The four Labour Codes unified the skeleton of the law; they did not remove the differences in how far each state has progressed with its own rules. Knowing the extent of a unification is where the analysis starts.
And there is an order to this decision. Settle your purpose, narrow your candidate states, obtain offers from more than one of them — and only then break ground. Logistics distance can be corrected afterwards with 3PL. Electricity tariffs, stamp duty, retrenchment requirements and incentive eligibility are all fixed the moment you break ground.
In our next article we will set out the five questions a board should ask when state selection comes before it as an agenda item.
📘 If You Would Like to Go Deeper into This Subject
There is material we could not fit into a single blog post and which is dealt with only in the book.
A practical concordance of the three lists in the Seventh Schedule — setting out which list each of your review items belongs to
The composition of a state incentive package and its prior registration requirements — covering exactly what is excluded when the deadline is missed
The case study in full — three years in the life of an automotive component manufacturer that concluded "the corporate tax rate is the same, so the state does not matter"
The five-axis framework for state selection — the five axes, each with an assessment of how far it can be undone
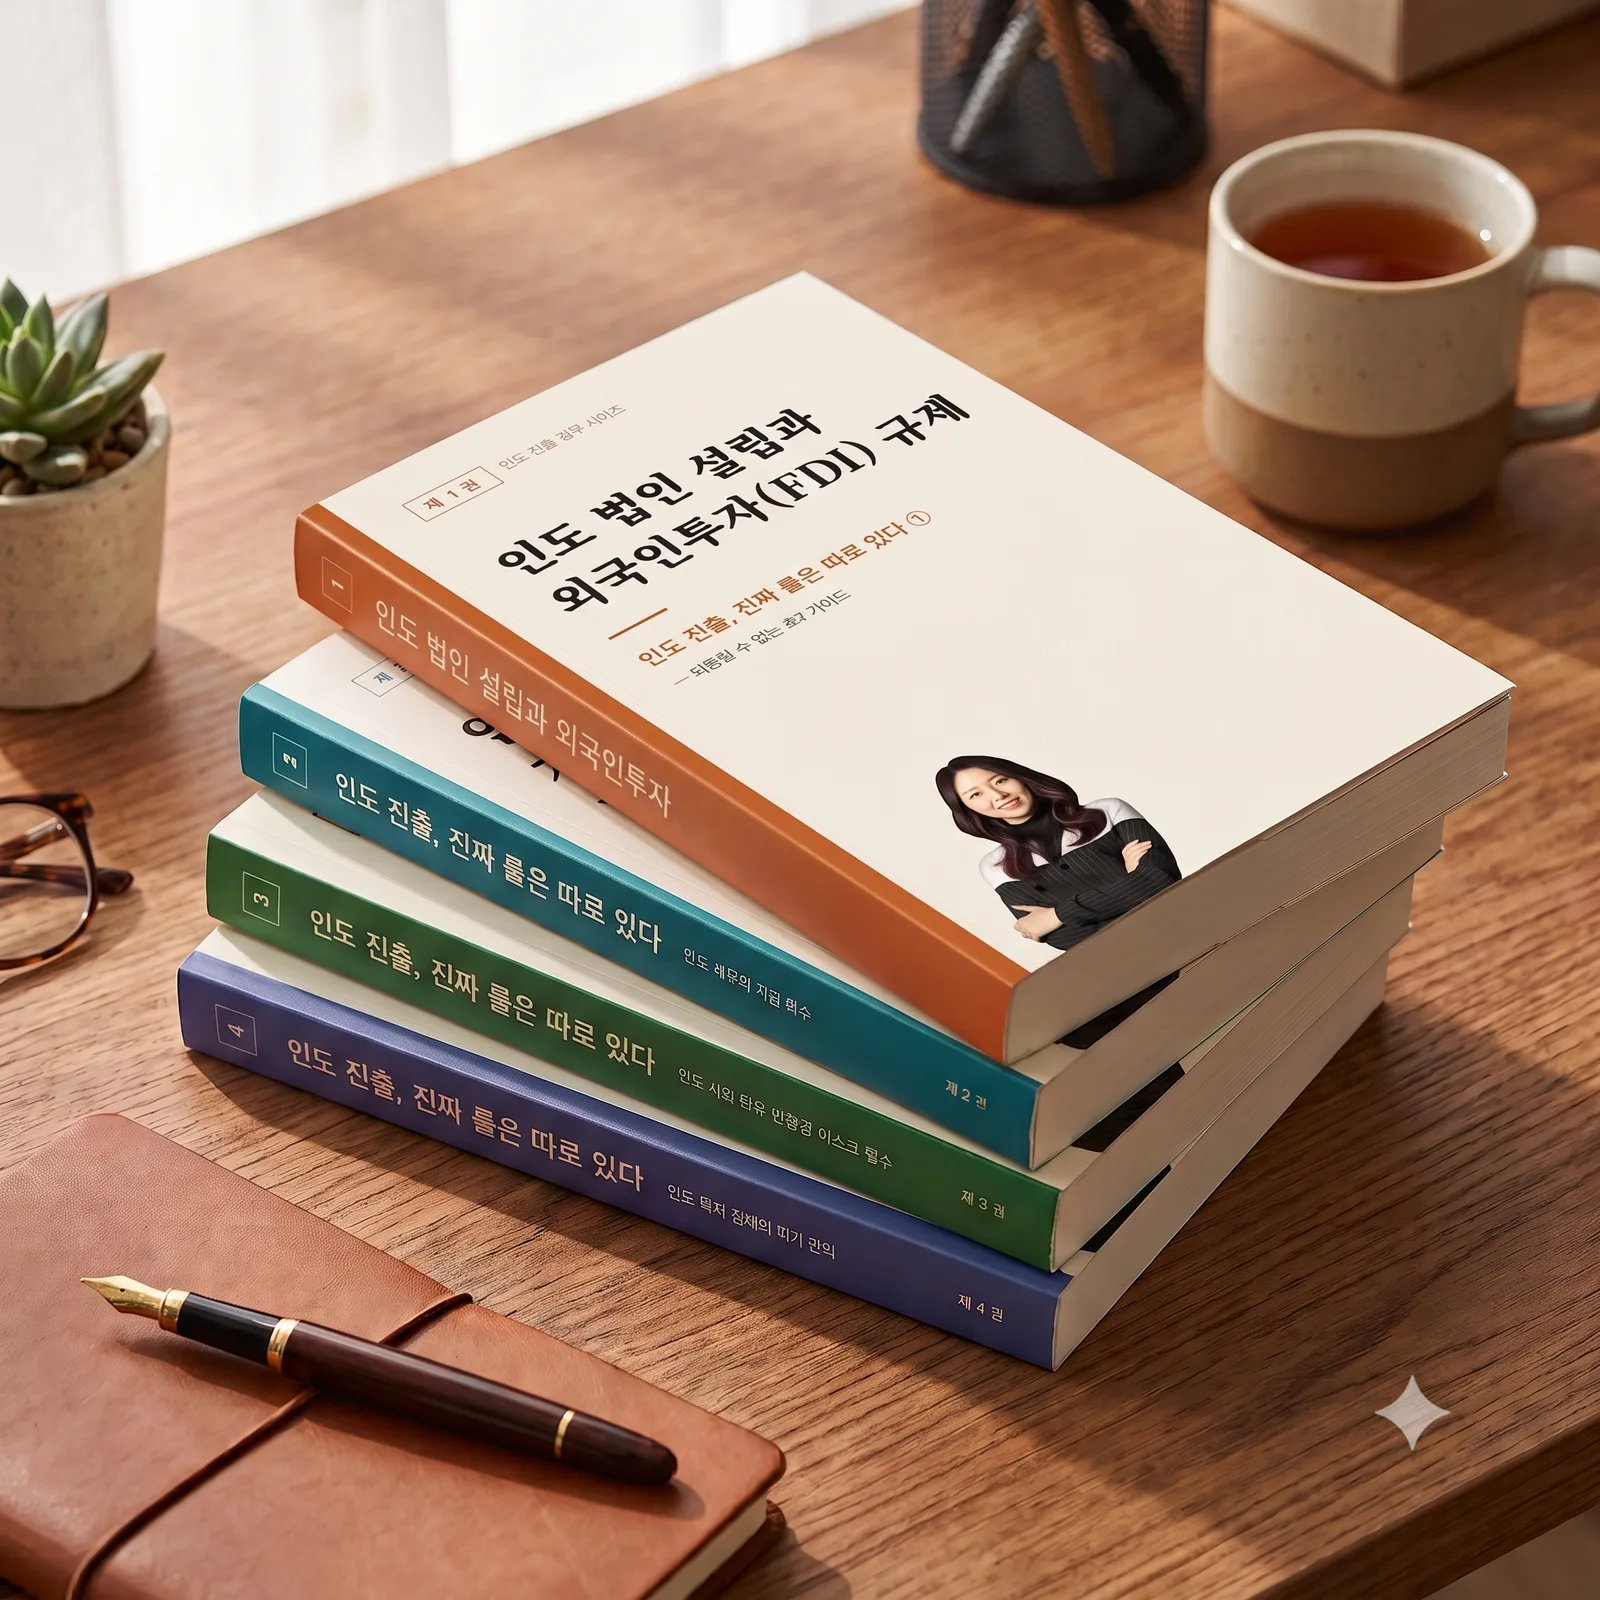
📗 India Incorporation and Foreign Direct Investment (FDI) Regulation, Volume 1 of India Entry: The Real Rules Are Elsewhere, is available from BOOKK.
If You Are Unsure Where to Begin with Your Entry into India
ADL Consulting has supported Korean companies entering India since establishing our Indian subsidiary in Delhi in 2017. We operate today from four bases — Delhi, Bengaluru, Chennai and Seoul — and have advised more than 100 companies and handled more than 300 licensing and government matters.
We support six fields from within a single team: incorporation, tax and accounting, certification and incentives, HR and legal, real estate, and distribution and marketing. ADL Consulting will be at your side as a dependable partner for your entry into the Indian market.