Hello, this is ADL Consulting.
"The board has already resolved to enter India. The site itself is being shortlisted by the working team." This is a state of play we hear often from companies preparing to enter the country. The sequence sounds natural enough. There is, however, an inversion buried inside it.
Choosing a site in India is not a decision about where to put up a building. It is a decision that fixes, for the next twenty years, the cost base of that establishment and the manner in which you will be able to manage its workforce. Most of it cannot be undone once you break ground.
In our previous article we set out why costs diverge from state to state even though the tax rate is the same across the country. Today we deal with how to choose the state itself — that is, with the five questions your board should be asking when the plant comes before it as an agenda item.
Key Points of This Article
For those of you who are pressed for time, we will begin with the conclusions.
State selection is not a property decision. It is a twenty-year decision about cost structure and labour flexibility.
There are five axes for your board to examine: labour flexibility, cost structure, incentives, administrative speed, and people and logistics.
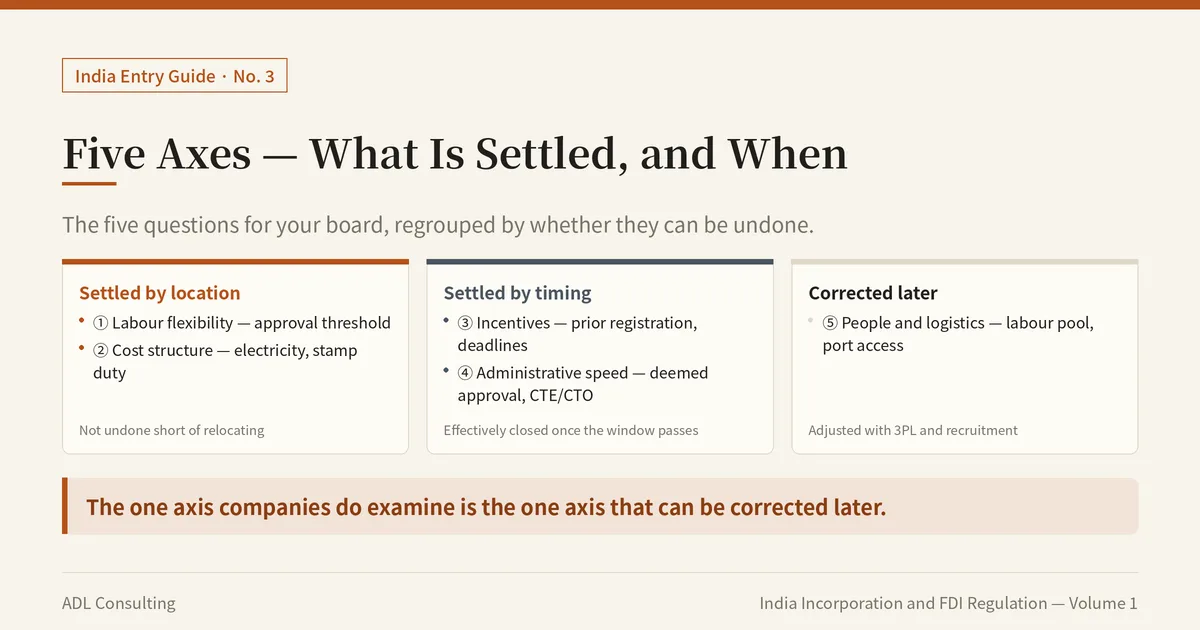
Of those five, only one — people and logistics — can be corrected afterwards. The other four are fixed the moment you break ground.
If you enquire about incentives after the investment has been settled internally, you will have no negotiating position left. Most states impose prior registration as a condition.
Keep at least three states on the table at the same time. Creating the competition is not a tactic within the negotiation; it is the substance of it.
1. What Happens the Moment It Is Delegated as a Property Matter
The decision is generally taken in two stages. The board resolves upon whether to go to India, and the question of where to build is passed down to the working team as a site review.
What goes into that review is the price of the land, the distance to the customer's plant, access to a port, and the labour pool nearby. Every one of those items is necessary. They also have one thing in common: they are all axes that can be corrected afterwards.
The items that are fixed when you break ground, by contrast, have no place in that form at all. Whether retrenchment requires the prior approval of the state government, what a unit of industrial electricity costs, what rate of stamp duty applies, and when the application window for incentives closes are not property questions.
The order of the review is therefore precisely inverted. What can be undone is examined in detail; what cannot be undone is not examined at all.
2. The Five Questions a Board Should Ask — a Framework for State Selection
The weighting will differ according to your purpose in entering India: domestic sales, a manufacturing base, sourcing and export, or R&D. Whatever that purpose, however, the following five axes should come before your board explicitly, and by name.
Axis | The question your board should ask | Can it be undone? |
|---|---|---|
① Labour flexibility | What is the threshold above which retrenchment or closure requires prior approval? Have the state rules under the Labour Codes been notified? | No |
② Cost structure | What are the industrial electricity tariff and the electricity duty? What is the rate of stamp duty and the price of industrial land? Is this a state that levies professional tax? | No |
③ Incentives | What is the scale of the capital subsidy and the SGST reimbursement? What are the prior registration requirements and the application deadlines? | Effectively no |
④ Administrative speed | Does the single-window regime contain a deemed approval provision? How long do CTE and CTO actually take? | No |
⑤ People and logistics | What is the skilled labour pool and the attrition rate? What is the access to ports and to your customer? | Partly |
The most important part of that table is not the middle column but the one on the right. Axes ① to ④ cannot be undone short of relocating the establishment altogether.
3. Only One of the Five Axes Can Be Undone
The axis that Korean companies in practice examine almost to the exclusion of the others is ⑤, people and logistics. It is also the only one of the five that can be corrected after the event.
Distance is largely absorbed by adding a warehouse or engaging a 3PL provider, and a shortage of particular skills can be addressed by widening your recruitment catchment.
An electricity tariff, however, cannot be negotiated downwards. Stamp duty once paid is not refunded. An incentive whose window has closed does not reopen. And the threshold for prior approval of retrenchment is not something a company is in a position to alter. By then the plant is standing on that state's land.
4. Putting Numbers to the Axes
It may help to translate axes that read as abstractions into the figures that actually sit behind them.
Axis | Where the divergence actually occurs |
|---|---|
Electricity | On publicly available data for 2025 compiled from the tariff orders of the state regulators, industrial tariffs are reported at approximately ₹7.55/kWh in Karnataka, ₹8.32 in Maharashtra, ₹8.98 in Gujarat and ₹9.04 in Tamil Nadu |
Stamp duty | Delhi levies a flat 6% (4% for a woman purchaser); Haryana divides the rate by area, at 7% in urban and 5% in rural districts |
Labour | Section 77 of the new Industrial Relations Code raised the threshold of 100 employees under the old Industrial Disputes Act to 300, but how warmly that figure is applied still depends on how far each state has progressed with its own notifications |
Administration | Telangana's TS-iPASS treats an application as approved in principle where the authorities have not responded within fifteen days |
A difference of one to one and a half rupees per unit reads as immaterial. For an electricity-intensive operation consuming 50 million kWh a year, however, a difference of ₹1.5 per unit comes to roughly ₹7.5 crore a year in operating profit — in the region of ₩1.2 billion. Set against a plant life of twenty years, that is a decision of a quite different order, and it is one no subsequent negotiation will recover.
Land differs again in its very nature. Industrial land in India is for the most part not an asset you buy on the open market but one allotted to you by a state industrial development corporation — GIDC in Gujarat, MIDC in Maharashtra, SIPCOT in Tamil Nadu, KIADB in Karnataka, and so on. The allotment criteria, the price, the obligation to commence operations within a set period and the resumption clause that applies if you do not are different at every one of them, so each must be checked for each candidate state separately.
※ Please note — the figures above vary with slabs, demand charges, time-of-day tariffs and the amendments each state makes. At the point of your actual review they should be re-confirmed against the latest tariff order and notifications.
5. A Case That Could Not Be Undone — Three Years of a 240-Employee Plant
A Korean automotive component manufacturer examined a local production base at the request of its customer. The conclusion reached by its head office finance team was that, since the corporate tax rate and GST are identical throughout India, state selection needed to take account of logistics distance and nothing further.
The company bought a private industrial estate 60 km from the customer's plant and broke ground on a facility of some 240 employees. Four months elapsed between the investment decision and groundbreaking, and the board treated that speed as evidence of execution. What emerged over the three years that followed was as follows.
Land — Buying private land meant bearing the stamp duty in full. Had the company taken an allotment on a development corporation estate in the neighbouring state, it would have been exempt, and the price per unit area would also have been lower.
Incentives — The application was made after groundbreaking, so the prior registration requirement was not met. With no other state on the table, there was no room to reopen the terms either.
Electricity — The tariff was roughly ₹1.2 per unit higher than in the neighbouring state. On annual consumption of 30 million kWh, that added approximately ₹3.6 crore a year, permanently.
Labour — In the third year the customer's orders fell away sharply. The state in question had not adopted the higher threshold, so an establishment of 240 employees required prior approval. Headcount was reduced only after a voluntary retirement scheme (VRS) paying compensation well above the statutory floor.
Payroll — The state levied professional tax, but the head office payroll system had no such field. The failure to register was picked up in the second-year audit, and back payments and a penalty followed.
The amount saved on logistics distance came to a few hundred million won a year. The cumulative loss across those five items ran to many times that figure. None of it could be undone.
6. The Order — Narrowing Down in Five Steps
First, settle your purpose in entering India. Second, screen down to five or six states that fit it. Third, compress that field to three using the five axes above. Fourth, submit the same investment proposal to the investment promotion agencies of all three states at the same time. Fifth, quantify the offers you receive and compare them on a twenty-year cash flow basis.
The step most often skipped is the fourth. If you settle the state internally and only then approach its development corporation to ask about incentives, your negotiating position is gone at that moment: a state government has no reason to put more than the standard package to a company that has already decided to come. Most states hold an individual negotiation provision for large investments, which makes competing the states against one another the route to terms beyond the standard package.
Submitting the same proposal matters as much as submitting it to three parties, because it is what allows the replies to be compared line by line rather than read one after another.
Frequently Asked Questions (FAQ)
Q1. You suggest narrowing to three states. Would two or four not do?
A. The number itself is not a rule. With two, the competition disappears the moment one drops out; with four or more, maintaining proposals of equal quality in parallel becomes difficult to sustain. Three tends to be the point of balance in practice.
Q2. If we apply after breaking ground, do we lose the incentives entirely?
A. It depends on the scheme and the state. The larger the item, however, the more likely it is that prior registration before the investment commences is a condition, so we would recommend confirming the deadlines at the same time as you shortlist the candidate states.
Q3. If our customer specifies a particular region, is there any room left to apply the five axes?
A. There usually is. Even where a region is specified, estates in the adjoining state can generally still be compared, and placing candidates close to the state border on the list costs very little in logistics distance.
Q4. If the plant has already been built, what can be done now?
A. The location itself is difficult to undo. The incentive items for which applications remain open, and any registration obligations that have been missed, can nevertheless be reviewed now.
In Closing
State selection is not a property decision. It is a twenty-year decision about cost structure and labour flexibility. Electricity tariffs, stamp duty, retrenchment requirements and incentive eligibility are all fixed the moment you break ground, and they remain on the profit and loss account for twenty years thereafter. The least reversible decision in an entry into India is not the form of the entity. It is the latitude and longitude.
In our next article we will turn to the axis on which there is most room to negotiate — state government incentives — and to the practice of obtaining offers from three states at once and comparing them.
📘 If You Would Like to Go Deeper into This Subject
There is material we could not fit into a single blog post and which is dealt with only in the book.
A due diligence checklist for each of the five axes — the questions to put to a candidate state, item by item
A comparison of allotment conditions across the state development corporations — the differences in commencement obligations and resumption clauses
The legal basis of a voluntary retirement scheme (VRS) — the exclusion from the definition of retrenchment, and the exemption requirements under the income tax legislation
A twenty-year cash flow comparison format — a frame for quantifying three offers on the same basis
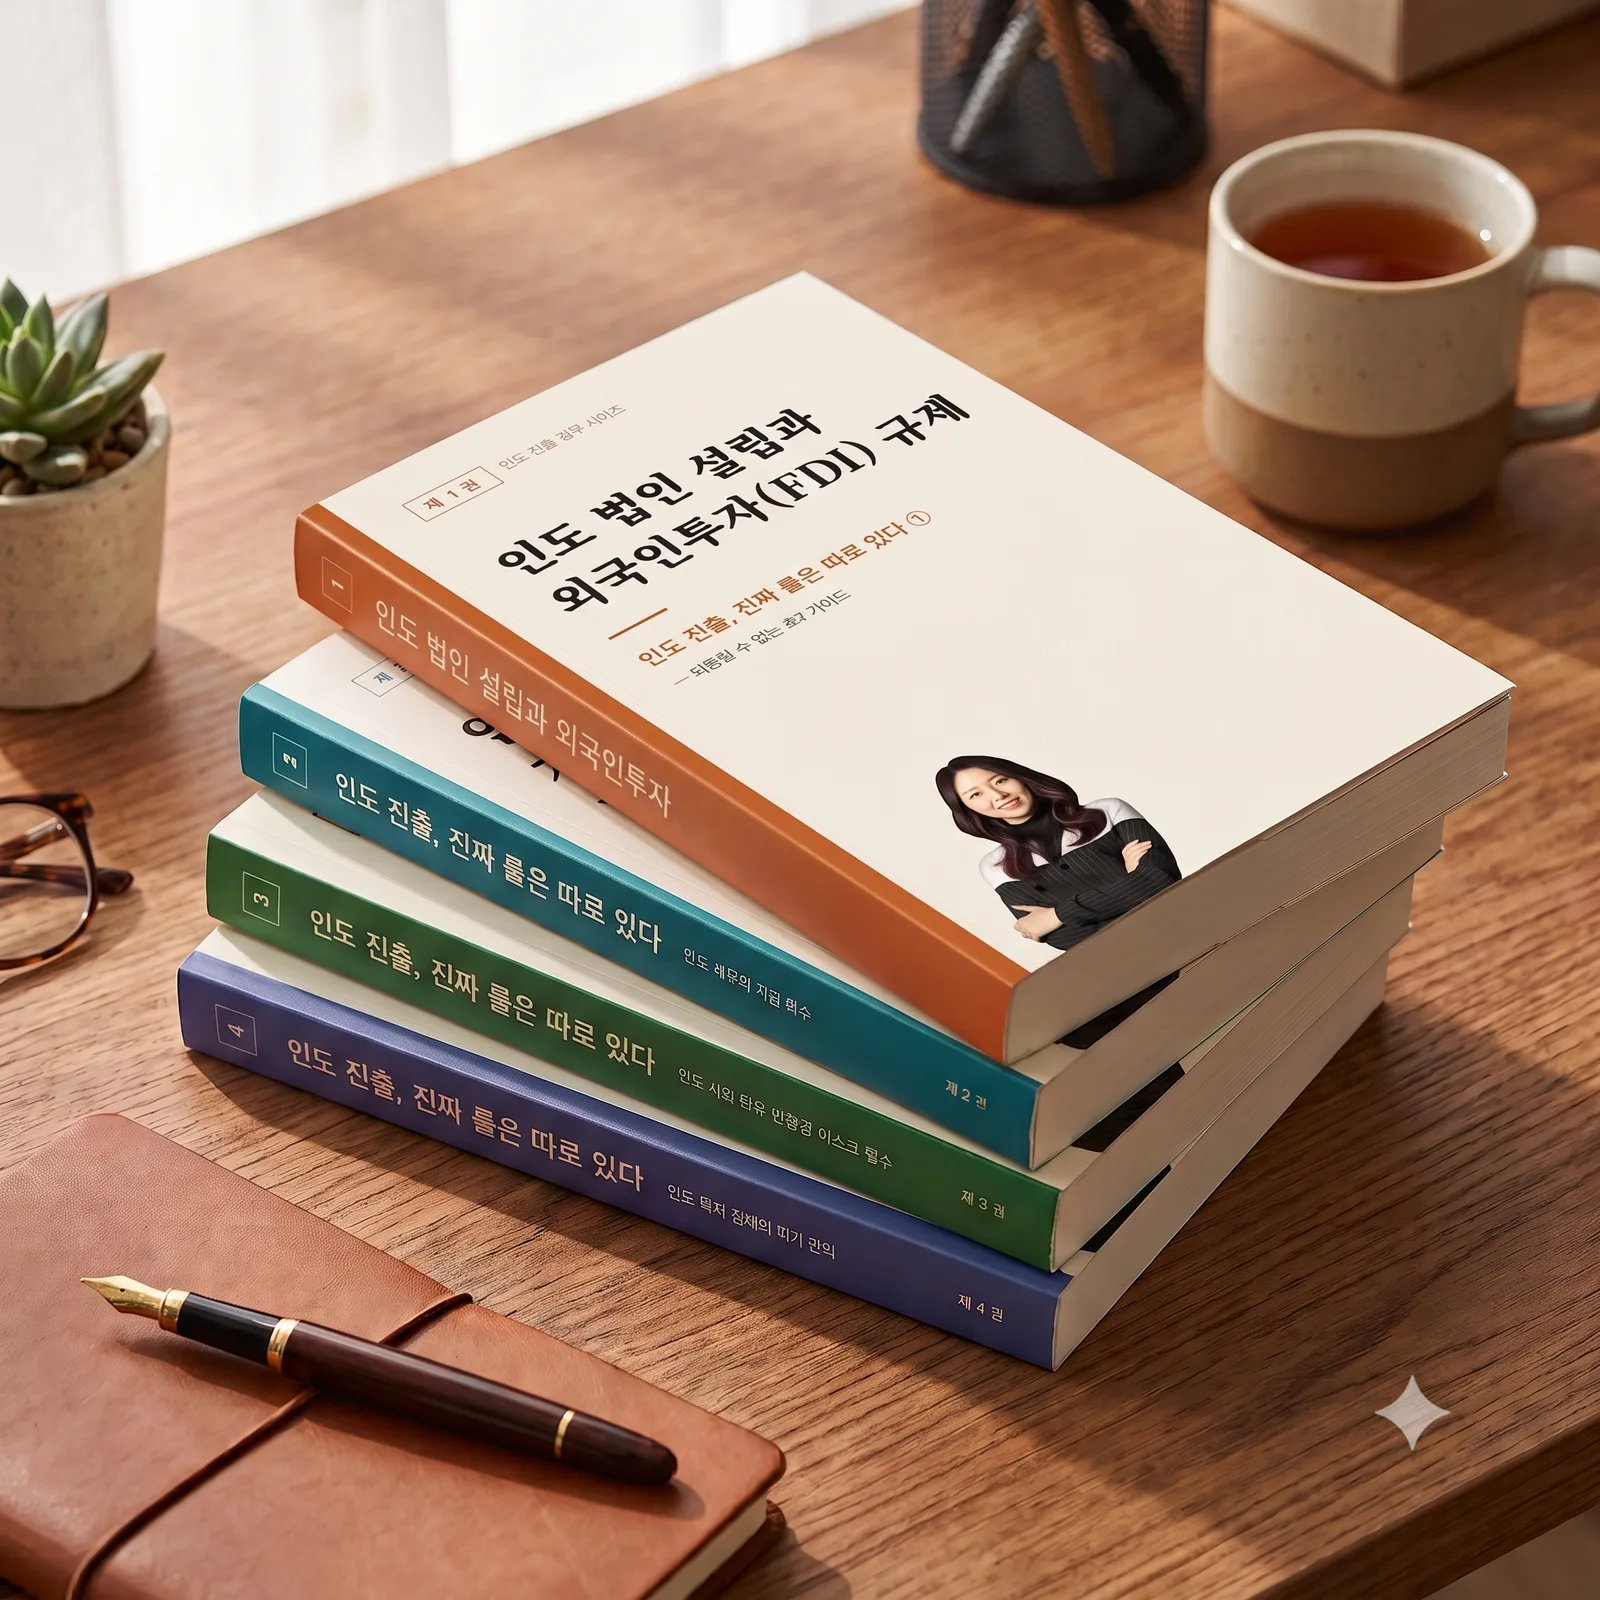
📗 India Incorporation and Foreign Direct Investment (FDI) Regulation, Volume 1 of India Entry: The Real Rules Are Elsewhere, is available from BOOKK.
If You Are Unsure Where to Begin with Your Entry into India
ADL Consulting has supported Korean companies entering India since establishing our Indian subsidiary in Delhi in 2017. We operate today from four bases — Delhi, Bengaluru, Chennai and Seoul — and have advised more than 100 companies and handled more than 300 licensing and government matters.
We support six fields from within a single team: incorporation, tax and accounting, certification and incentives, HR and legal, real estate, and distribution and marketing. ADL Consulting will be at your side as a dependable partner for your entry into the Indian market.